
What happens to a street vendor, a construction worker, or a domestic helper when they turn 60 and their body can no longer keep up with daily labour? There is no company pension waiting for them, no provident fund, no retirement corpus. For nearly 42 crore unorganised workers in India, old age often means depending on children or falling back into poverty. The PM Shram Yogi Maandhan Yojana was launched to change exactly that — a government-backed pension scheme that guarantees ₹3,000 every month after the age of 60, with the government matching every rupee you contribute.
✅ This guide is based on official government sources and notifications. Last verified: October 15, 2026. Scheme details, eligibility criteria, and benefit amounts are revised by the government from time to time — always cross-check the latest information on the official portal before applying.
What Is PM Shram Yogi Maandhan Yojana? A Simple Explanation
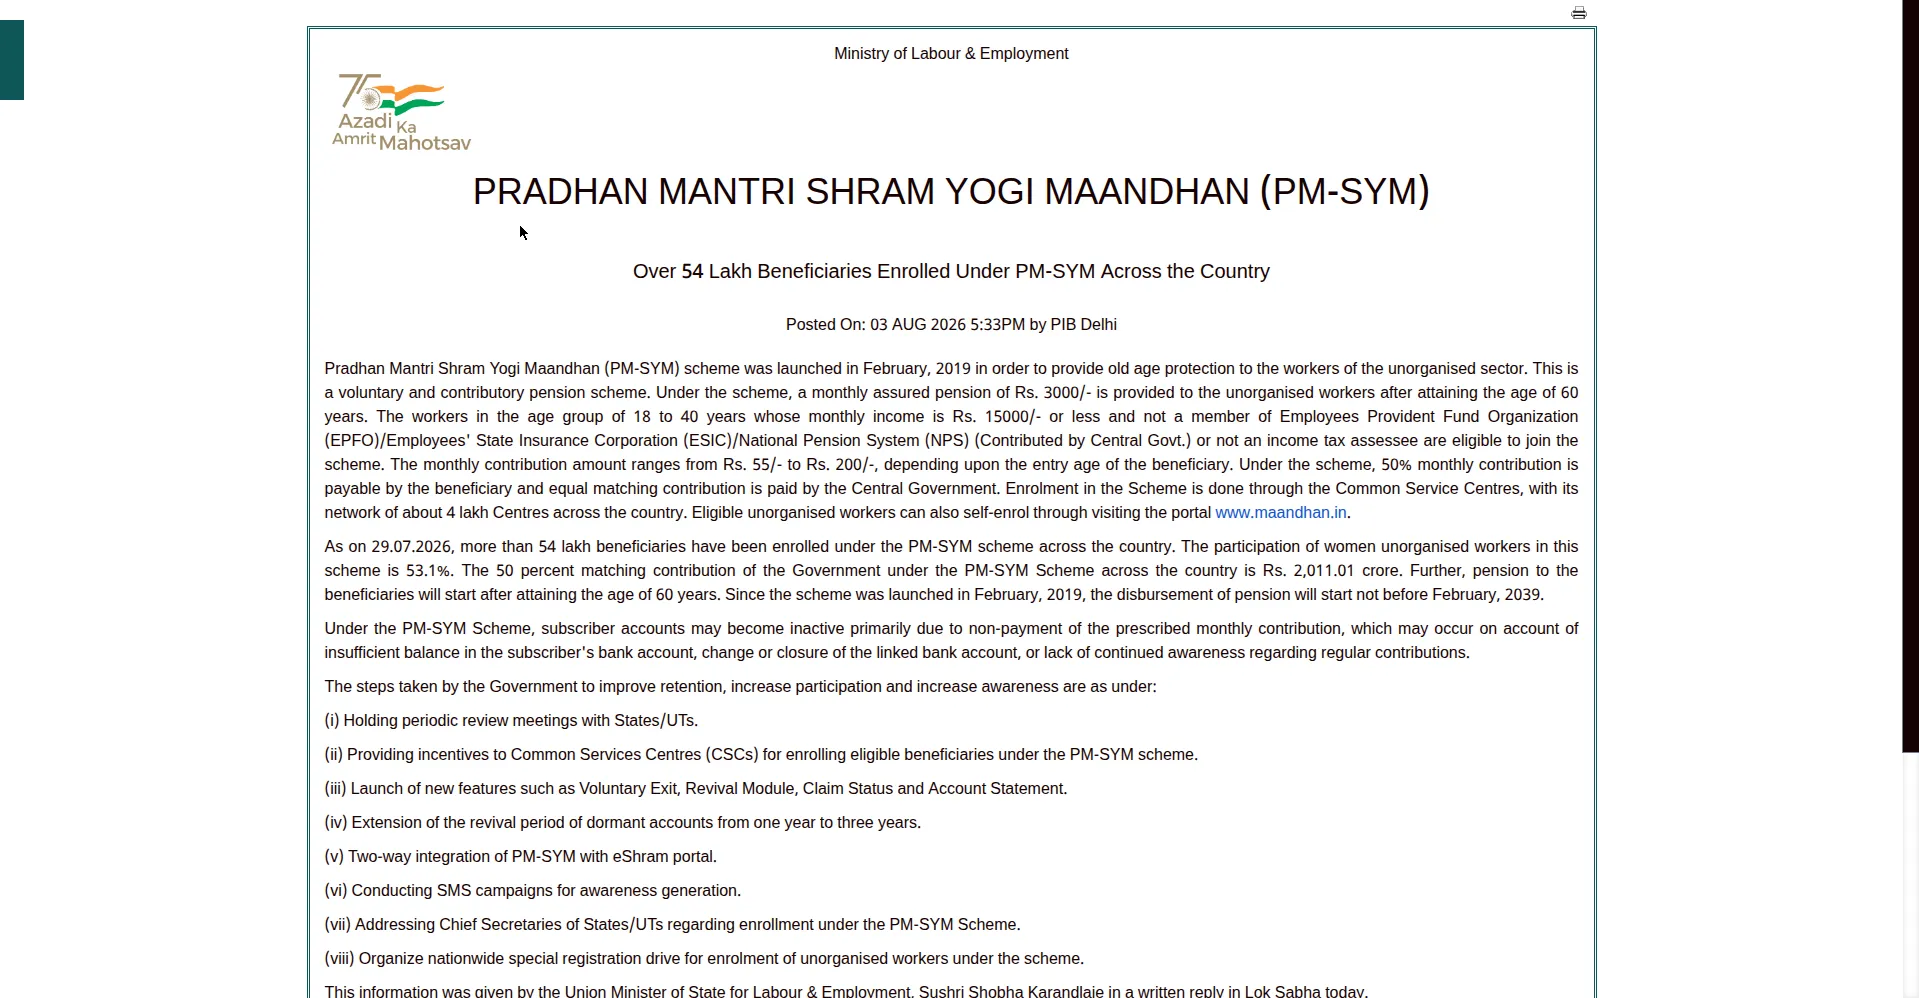
The Pradhan Mantri Shram Yogi Maandhan Yojana, usually shortened to PM-SYM, is a voluntary and contributory pension scheme run by the Ministry of Labour and Employment. It was launched on 15 February 2019, and it is aimed squarely at workers in the unorganised sector — the people who keep the economy running but have no formal employer to save for their retirement.
Here is the deal in one line: if you are between 18 and 40 years old, earn up to ₹15,000 a month from unorganised work, and are not already covered by EPFO, ESIC, or NPS, you can join PM-SYM by paying a small monthly amount. The amount depends on the age at which you join — it starts at just ₹55 a month if you join at 18 and goes up to ₹200 a month if you join at 40. The Government of India puts in the exact same amount as you, rupee for rupee, every single month. You keep paying until you turn 60, and from 60 onwards you receive an assured pension of ₹3,000 per month for the rest of your life.
PM Shram Yogi Mandhan Yojana is the government’s pension scheme for unorganised workers — this PM Shram Yogi Mandhan Yojana guide explains who can join, what you pay each month, and how to apply online in simple steps.
When I first looked into this scheme, what struck me was how deliberately simple the government kept it. There is no market risk like in NPS, no complicated fund choices, no lock-in confusion. You pay a fixed small amount, the government matches it, and you get a fixed pension. That simplicity is the whole point — the scheme is meant for workers who may never have dealt with banks or financial products before.
The pension is paid through an auto-debit facility from your savings bank account or Jan-Dhan account, so once you enrol, the contribution goes out automatically every month. On successful enrolment, a Shram Yogi Pension Account Number is generated and you get a Shram Yogi Card as proof of membership.
Key Benefits of PM Shram Yogi Maandhan Yojana
Let us walk through what you actually get, because the benefits go beyond the headline ₹3,000 figure.
Assured monthly pension of ₹3,000. After you turn 60, you receive ₹3,000 every month for life. This is not linked to markets or interest rates — it is a fixed, guaranteed amount. For a worker who has never had any retirement income, ₹3,000 a month covers basic food and medicine expenses and, just as importantly, preserves dignity and independence in old age.
Government matches your contribution 1:1. This is the most powerful feature of the scheme. If you pay ₹80 a month, the Central Government deposits another ₹80 into your pension account. So your effective investment doubles instantly. There are very few schemes in India where the government matches your savings rupee for rupee.
Family pension of ₹1,500 for the spouse. If the pension holder passes away after pension has started, the spouse continues to receive 50% of the pension — ₹1,500 per month — for life. This protects the surviving partner from being left with nothing.
Protection if you die before 60. If the subscriber dies before reaching pension age, the spouse has two options: continue the scheme by paying the regular contributions and receive the full pension after 60, or exit the scheme and withdraw the entire contribution corpus along with the accumulated interest. Either way, the family is not left empty-handed.
Couples can double the benefit. If both husband and wife enrol separately, each gets ₹3,000 after 60 — a combined household pension of ₹6,000 a month. For a retired worker couple, that is genuinely meaningful money.
Missed payments can be fixed. Life happens — sometimes a payment fails because the bank balance was low. The scheme allows you to regularise missed contributions by paying the outstanding dues. Some penalties may apply depending on how long the gap was, but you do not lose your membership for a missed month.
Who Is Eligible? PM Shram Yogi Maandhan Yojana Eligibility Criteria
Eligibility is straightforward, but you need to check every condition because the scheme is strict about who qualifies.
- Age: You must be between 18 and 40 years old at the time of joining. Once you join, you keep contributing until 60.
- Monthly income: Your monthly income should not exceed ₹15,000. This scheme is for low-income unorganised workers.
- Occupation: You must be an unorganised worker. The official list includes street vendors, rickshaw pullers, head loaders, construction workers, domestic workers, agricultural labourers, beedi workers, brick kiln workers, washermen, leather workers, tailors, mid-day meal workers, cobblers, handloom workers, drivers, plumbers, garbage pickers, and similar occupations.
- Not covered elsewhere: You must NOT be a member of EPFO (Employees’ Provident Fund), ESIC (Employees’ State Insurance Corporation), or NPS (National Pension System). If you already have formal social security, you cannot join.
- Taxpayer exclusion: You should not be an income tax payer.
- Documents: You need an Aadhaar card, a savings bank account or Jan-Dhan account (for auto-debit), and a mobile number linked to Aadhaar.
One question I see a lot: can a student join? If a student also does part-time unorganised work and meets the income and age conditions, they can technically enrol. But the scheme is really designed for full-time informal workers, so apply only if you genuinely fit the worker definition.
Age-Wise Monthly Contribution Chart (Official)
This is the part most people search for, so let me lay it out completely. Your monthly contribution is fixed based on the age at which you join — it never changes afterwards. The government contributes the same amount as you.
| Entry Age | Your Monthly Contribution | Government Contribution | Total/Month |
|---|---|---|---|
| 18 | ₹55 | ₹55 | ₹110 |
| 19 | ₹58 | ₹58 | ₹116 |
| 20 | ₹61 | ₹61 | ₹122 |
| 21 | ₹64 | ₹64 | ₹128 |
| 22 | ₹68 | ₹68 | ₹136 |
| 23 | ₹72 | ₹72 | ₹144 |
| 24 | ₹76 | ₹76 | ₹152 |
| 25 | ₹80 | ₹80 | ₹160 |
| 26 | ₹85 | ₹85 | ₹170 |
| 27 | ₹90 | ₹90 | ₹180 |
| 28 | ₹95 | ₹95 | ₹190 |
| 29 | ₹100 | ₹100 | ₹200 |
| 30 | ₹105 | ₹105 | ₹210 |
| 31 | ₹110 | ₹110 | ₹220 |
| 32 | ₹120 | ₹120 | ₹240 |
| 33 | ₹130 | ₹130 | ₹260 |
| 34 | ₹140 | ₹140 | ₹280 |
| 35 | ₹150 | ₹150 | ₹300 |
| 36 | ₹160 | ₹160 | ₹320 |
| 37 | ₹170 | ₹170 | ₹340 |
| 38 | ₹180 | ₹180 | ₹360 |
| 39 | ₹190 | ₹190 | ₹380 |
| 40 | ₹200 | ₹200 | ₹400 |
The takeaway is simple: the earlier you join, the less you pay. An 18-year-old pays just ₹55 a month — less than the cost of a single tea-and-snack outing — while a 40-year-old pays ₹200. That is why, if you are eligible and under 30, joining sooner rather than later genuinely saves you money over the life of the scheme.
Let me put real numbers on it. Say you join at 25. You pay ₹80 a month for 35 years. That is 80 × 12 × 35 = ₹33,600 out of your own pocket over the entire period. The government puts in another ₹33,600. And from age 60, you get ₹3,000 a month — ₹36,000 a year — for life. You recover your entire lifetime contribution in less than one year of pension. That is the math that makes this scheme worth a serious look.
PM Shram Yogi Maandhan Yojana Apply Online: Step-by-Step Registration
There are two ways to enrol: self-enrolment on the official portal maandhan.in, or through your nearest Common Service Centre (CSC). Both work fine — pick whichever is easier for you.
Method 1: Self-Enrolment on maandhan.in
- Open the official website maandhan.in on your phone or computer. (Type the address carefully — use only the official site.)
- Click on “Self Enrollment” or “Register Now”.
- Enter your mobile number and verify it with the OTP you receive.
- Enter your Aadhaar number. Make sure the mobile number linked to your Aadhaar is active, because OTPs will come there.
- Fill in your bank account details — account number and IFSC code. This account will be used for the monthly auto-debit.
- Select your occupation from the list of unorganised worker categories.
- Confirm your monthly contribution amount (it will be auto-filled based on your age).
- Authorise the auto-debit mandate so contributions go out automatically every month.
- Submit the form. After your first contribution is processed, your Shram Yogi Pension Card is generated — download it and keep it safe.
Method 2: Enrol Through the Nearest CSC
If you are not comfortable doing this online, walk into the nearest Common Service Centre with your Aadhaar card and bank passbook. The CSC operator will fill the form for you, verify your documents, and complete the enrolment in about 15 minutes. You will get a printed acknowledgement on the spot. Many workers I have spoken to prefer this route because the operator handles the technical parts.
A practical tip: whichever method you choose, double-check the bank account details before submitting. Auto-debit failures are the most common reason for missed contributions, and they almost always trace back to a wrong account number or IFSC entered during registration.
Documents Required for PM-SYM Registration
Keep these ready before you start, so the process takes minutes instead of multiple visits:
- Aadhaar card — mandatory for identity verification.
- Savings bank account or Jan-Dhan account — with account number and IFSC code, for monthly auto-debit.
- Mobile number linked to Aadhaar — OTPs for verification come here.
- Nominee details — name and relationship of the person who should receive benefits.
That is genuinely the whole list. No income certificate, no caste certificate, no employer letter. The government kept documentation minimal on purpose so that informal workers are not shut out by paperwork.
PM-SYM vs Atal Pension Yojana: Which Is Better for You?
People often confuse these two because both are government pension schemes with “pension after 60” in the pitch. Here is how they differ:
| Feature | PM Shram Yogi Maandhan | Atal Pension Yojana |
|---|---|---|
| Target group | Unorganised workers only | Any Indian citizen 18–40 |
| Pension amount | Fixed ₹3,000/month | ₹1,000–₹5,000 (you choose) |
| Government contribution | Matches your amount 1:1 | No matching (limited co-contribution ended) |
| Income limit | Up to ₹15,000/month | No income limit (taxpayers excluded since Oct 2022) |
| EPFO/ESIC members | Not eligible | Eligible |
| Family pension | 50% (₹1,500) to spouse | Same pension to spouse |
| Ministry | Labour and Employment | Finance (PFRDA administered) |
Short version: if you are an unorganised worker earning under ₹15,000, PM-SYM is usually the better deal because the government matches your money. If you want a higher pension slab (up to ₹5,000) or you are already in EPFO, Atal Pension Yojana fits better. You cannot be in both PM-SYM and NPS, but comparing PM-SYM against APY is a legitimate choice to make.
Exit Rules, Missed Payments, and What Happens on Death
These are the questions people ask after the basics, and honest answers matter here.
Can you exit the scheme early? Yes. If you exit before completing 10 years, you get back your contributions with savings-bank interest. If you exit after 10 years but before 60, you get your contributions with accumulated interest (or the actual fund return, as per scheme rules). The government’s matching contribution is handled as per the exit provisions — the key point is you do not lose everything for leaving early.
What if a monthly payment is missed? You can regularise it by paying the outstanding amount. The scheme allows revival of lapsed accounts within the permitted window, though penalties may apply for long gaps. The practical advice: keep enough balance in the linked account a day or two before the debit date.
What if the subscriber dies before 60? As covered above, the spouse can either continue the scheme (paying the same contributions, and receiving the full ₹3,000 pension after 60) or exit and take the accumulated corpus with interest.
What if the subscriber dies after pension starts? The spouse receives a family pension of ₹1,500 per month (50%) for life.
Is the pension taxable? Pension income is generally taxable as per income tax slabs, but at ₹36,000 a year, most PM-SYM pensioners fall below the taxable threshold. Still, tax rules change — treat this as a general note, not tax advice.
Common Mistakes to Avoid When Applying
In my experience helping people understand this scheme, these are the errors that cause the most rejections and delays:
- Applying while enrolled in EPFO/ESIC/NPS. The system cross-checks. If you have a UAN from a previous formal job, you are not eligible — even if you are currently doing informal work.
- Wrong bank details. A single wrong digit in the account number or IFSC means auto-debit fails every month. Copy them directly from your passbook.
- Aadhaar-mobile mismatch. If your mobile number is not linked to Aadhaar, OTP verification fails and registration stalls. Update it at an Aadhaar centre first.
- Using unofficial websites. Only maandhan.in and authorised CSCs handle enrolment. Random “apply online” sites asking for fees are not part of the scheme.
- Waiting until 40 to join. Every year you delay, your monthly contribution rises. Joining at 25 instead of 35 saves you ₹70 a month for 25+ years.
How PM-SYM Fits With E-Shram Registration
If you have heard of the e-Shram card, you might wonder how it connects. E-Shram is the national database of unorganised workers — it registers you and gives you a UAN-style identity, plus access to accident insurance. PM-SYM is the pension product. They complement each other: e-Shram identifies you as an unorganised worker, and PM-SYM gives you the retirement pension. Ma
PM Shram Yogi Mandhan Yojana: Final Takeaway
One more thing about PM Shram Yogi Mandhan Yojana: the earlier you join PM Shram Yogi Mandhan Yojana, the less you pay every month. An 18-year-old pays just Rs 55 under PM Shram Yogi Mandhan Yojana, while a 40-year-old pays Rs 200 — the PM Shram Yogi Mandhan Yojana contribution chart rewards early birds joining PM Shram Yogi Mandhan Yojana.
Ready to enrol in PM Shram Yogi Mandhan Yojana? Visit the official PM Shram Yogi Mandhan Yojana portal at maandhan.in and choose Self Enrollment. The PM Shram Yogi Mandhan Yojana registration takes about fifteen minutes, and your PM Shram Yogi Mandhan Yojana pension card is generated after the first contribution.
Confused about PM Shram Yogi Mandhan Yojana? Call the PM Shram Yogi Mandhan Yojana helpline 18002676888 for help with your PM Shram Yogi Mandhan Yojana application, PM Shram Yogi Mandhan Yojana eligibility, or PM Shram Yogi Mandhan Yojana contribution amount. Remember, PM Shram Yogi Mandhan Yojana enrolment is free — never pay any agent for PM Shram Yogi Mandhan Yojana registration.
Quick PM Shram Yogi Mandhan Yojana recap: PM Shram Yogi Mandhan Yojana gives Rs 3,000 every month after 60, the government matches your PM Shram Yogi Mandhan Yojana contribution 1:1, and your spouse gets Rs 1,500 family pension. If you are an unorganised worker, PM Shram Yogi Mandhan Yojana is the simplest pension you will find — share this PM Shram Yogi Mandhan Yojana guide with fellow workers.
Bookmark this PM Shram Yogi Mandhan Yojana guide and check the PM Shram Yogi Mandhan Yojana contribution chart for your age before applying. PM Shram Yogi Mandhan Yojana works best when you start early — begin your PM Shram Yogi Mandhan Yojana enrolment today.
Still wondering whether PM Shram Yogi Mandhan Yojana suits you? If you are between 18 and 40, earn under Rs 15,000, and work in the unorganised sector, PM Shram Yogi Mandhan Yojana was designed for exactly you — read the PM Shram Yogi Mandhan Yojana eligibility section above once more and take the first step.
ny CSC operators enrol workers in both in a single visit. If you already have an e-Shram card, carry it when you go for PM-SYM enrolment — it speeds up occupation verification.
Frequently Asked Questions
What is the monthly pension amount in PM Shram Yogi Maandhan Yojana?
You receive an assured pension of ₹3,000 per month after turning 60, for life. If the subscriber dies after pension begins, the spouse gets ₹1,500 per month as family pension.
How much do I need to contribute every month?
It depends on your entry age: ₹55/month at 18, ₹80 at 25, ₹100 at 29, ₹105 at 30, ₹150 at 35, and ₹200 at 40. The government contributes the exact same amount, so your pension account grows by double what you pay.
How can I apply for PM Shram Yogi Maandhan Yojana online?
Visit maandhan.in, choose Self Enrollment, verify your mobile with OTP, enter Aadhaar and bank details, select your occupation, authorise auto-debit, and submit. Alternatively, visit the nearest CSC with Aadhaar and bank passbook.
Who is not eligible for PM-SYM?
Workers already enrolled in EPFO, ESIC, or NPS, income tax payers, organised-sector employees, and anyone above 40 or earning more than ₹15,000 a month cannot join.
What happens to my money if I exit the scheme early?
You can exit and receive your contributions back with interest — savings-bank interest if you exit before 10 years, accumulated interest if after 10 years but before 60. You do not forfeit everything.
Can both husband and wife join PM Shram Yogi Maandhan Yojana?
Yes. Each eligible spouse can enrol separately and each receives ₹3,000/month after 60 — a combined ₹6,000/month household pension.
Final Thoughts: Is PM-SYM Worth It?
For the worker it was built for — an unorganised worker between 18 and 40 earning under ₹15,000 — this is one of the simplest yes decisions in Indian personal finance. The government literally doubles your money every month, the pension is guaranteed rather than market-linked, and the paperwork is minimal. The main risk is not the scheme itself but delay: every year you wait, the entry contribution climbs.
If you are eligible, do not overthink it. Check your eligibility against the list above, keep your Aadhaar and bank details ready, and enrol either on maandhan.in or at your nearest CSC. Your 60-year-old self will thank you. And if this helped, share it with someone doing informal work — most eligible workers still have not heard of this scheme. For related reading, see our guides on e-Shram card registration and government pension options for workers.