
Can you start a real government-backed pension with just ₹250? Until this year, most of India’s informal workers would have said no. PFRDA’s answer to that question is NPS Sanchay — a simplified version of the National Pension System built for small savers, street vendors, domestic workers, drivers and the self-employed who never got a PF or employer pension.
✅ This guide is based on official government sources and notifications. Last verified: October 12, 2026. Scheme details, eligibility criteria, and benefit amounts are revised by the government from time to time — always cross-check the latest information on the official portal before applying.
I first heard about NPS Sanchay when PFRDA started its Pension Yatra camps earlier this month, and honestly, the ₹250 figure stopped me mid-scroll. I’ve been writing about the regular NPS for years — I even maintain a detailed NPS guide on this site — and the biggest complaint readers share is that the regular NPS feels complicated: choose a pension fund, pick active or auto allocation, decide equity exposure. NPS Sanchay throws all of that out at the start. You put in ₹250, and the money goes into a ready-made, government-sector-style investment pattern. No decisions needed.
In this guide, I’ll walk you through everything: NPS Sanchay kya hai, the scheme details, who is eligible, the age limit, the interest rate question (it’s not what you think), how to open an account step by step, and how it compares with regular NPS and Atal Pension Yojana. By the end, you should be able to open an account on your own without anyone’s help.
NPS Sanchay Kya Hai? (What Is NPS Sanchay)
NPS Sanchay is a simplified variant of the National Pension System, launched by the Pension Fund Regulatory and Development Authority (PFRDA) through a circular in May 2026. PFRDA then took it nationwide on NPS Diwas, October 1, 2026, alongside the NPS Sanchay Pension Yatra — a ground-level awareness drive with camps in Delhi, Ahmedabad, Bengaluru and Kolkata, where on-the-spot accounts are opened through “Tatkal NPS” assisted channels. Twelve more yatras are planned over the following six months.
Think of it this way. Regular NPS is a powerful pension product, but it asks a first-time saver to make investment decisions — pick a pension fund manager, choose between active and auto asset allocation, set equity exposure. For someone who has never seen a mutual fund statement, that screen is a wall. NPS Sanchay keeps the NPS engine but removes the wall:
- ₹250 to open, ₹10 onwards afterwards. That’s genuinely the whole entry barrier.
- No yearly minimum. Skip a month or six; the account doesn’t freeze on you.
- No investment choices at the start. Your money goes into a predefined pattern that mirrors the government-sector NPS investment pattern — roughly 75% in government securities and corporate bonds, 25% in equity. You can change the pattern later if you want.
- Same NPS rules underneath. Exit, partial withdrawal and tax benefits follow the regular NPS framework, so nothing about Sanchay is a “lite” product with weaker protections.
NPS Sanchay is aimed at the crores of informal-sector workers — street vendors, domestic help, drivers, gig workers — who have no PF or employer pension.
NPS Sanchay Scheme Details (Key Facts at a Glance)
Here is the complete scheme profile in one table, based on the PFRDA circular and the NPS Diwas rollout coverage:
| Parameter | NPS Sanchay Detail |
|---|---|
| Regulator | PFRDA (Pension Fund Regulatory and Development Authority) |
| Launched | PFRDA circular, May 2026; nationwide rollout on NPS Diwas, October 1, 2026 |
| Minimum contribution | ₹250 at account opening; ₹10 for subsequent contributions |
| Mandatory annual contribution | None — no yearly minimum |
| Age limit | Indian citizens aged 18 to 85 years |
| Investment pattern | Predefined default mirroring government-sector NPS (75% govt securities + corporate bonds, 25% equity); changeable later |
| Exit and withdrawal | PFRDA (Exits and Withdrawals) Regulations, 2015 — same as regular NPS |
| Charges | Same as NPS common schemes (PoP onboarding fee ₹200 via PoP / ₹100 digital; 0.20% p.a. of AUM, GST extra) |
| Account opening channels | Online (e-NPS), banks, Points of Presence (PoPs), Common Service Centres (CSCs), Tatkal NPS at Pension Yatra camps |
| Tax benefits | Same as NPS — Sections 80CCD(1) and 80CCD(1B) |
NPS Sanchay Eligibility: Kaun Account Khol Sakta Hai?
The eligibility bar is deliberately low. You can open an NPS Sanchay account if:
- You are an Indian citizen (resident or non-resident).
- You are between 18 and 85 years old.
- You complete standard KYC — Aadhaar, PAN and a bank account are the practical essentials — and fill the Subscriber Registration Form.
That is genuinely it. There is no income proof requirement, no employment condition, and no need to be salaried. A street vendor, a domestic worker, a gig driver, a small shop owner, a freelancer — everyone is welcome. This is the opposite of most pension products in India, which quietly assume a salaried life with predictable monthly income.
One thing to note: a person can hold only one NPS Sanchay Tier-I account. If you already have a regular NPS Tier-I account (PRAN), you don’t need a second one — you already have the underlying product. Sanchay is a simplified on-ramp for people who don’t have an NPS account yet, not a second bucket for existing NPS subscribers.
NPS Sanchay Age Limit: 18 Se 85 Tak
The age limit for NPS Sanchay is 18 to 85 years. This is worth pausing on, because it’s actually more generous than the regular NPS, where fresh Tier-I account opening typically stops at 70.
Why does that matter? A 60-year-old street vendor who spent 35 years with zero pension coverage can still open a Sanchay account and start contributing. Even 5-10 years of contributions build a corpus that buys a small annuity at exit. The pension maths won’t match someone who started at 25, but something is infinitely better than the nothing most informal workers retire with.
Remember the basic NPS rhythm still applies: the normal exit age is 60, at which point you use part of the corpus to buy an annuity (monthly pension) and take the rest as a lump sum. Opening at a higher age simply means a shorter accumulation window — the rules don’t penalize you for joining late.
If your parents are already 60 or older and you’re looking for something safer with guaranteed returns, read my guide on the Senior Citizen Savings Scheme (SCSS) — it currently offers one of the highest assured rates among government schemes for seniors.
NPS Sanchay Account Opening: Step-by-Step Process
This is the section I want you to read carefully, because the whole point of Sanchay is that you can do this yourself. You have five doors to walk through — pick whichever is closest to you.
Option 1: Open Online via e-NPS
- Visit the official e-NPS portal (linked from pfrda.org.in) and choose to open a new NPS account.
- Register using your mobile number and verify the OTP.
- Complete e-KYC with Aadhaar (OTP-based) or offline KYC with your documents.
- Fill in personal details, nominee details and bank details.
- Make the first contribution of ₹250 minimum via UPI, net banking or debit card.
- Your PRAN (Permanent Retirement Account Number) is generated and your Sanchay account is active.
Online onboarding also keeps you free of PoP charges: subscribers who open through e-NPS and keep contributing through e-NPS or D-Remit don’t pay the PoP onboarding fee at all.
Option 2: Through a Bank or Point of Presence (PoP)
Walk into any bank that acts as an NPS Point of Presence with your Aadhaar, PAN, a passport-size photo and your bank account details. Fill the Subscriber Registration Form, make your ₹250 first contribution, and the bank staff will generate your PRAN. From October 1, 2026, PoP onboarding carries a one-time ₹200 fee (collected as ₹50 per quarter through unit cancellation, GST extra), or ₹100 for a fully digital non-face-to-face onboarding.
Option 3: Through a Common Service Centre (CSC)
Nearly every block in India has a CSC kiosk, and PFRDA has specifically pushed Sanchay through these. Carry Aadhaar, PAN and your bank passbook. The CSC operator fills the form digitally, you contribute ₹250, and you’re done. For first-time digital users, this assisted route removes every bit of friction.
Option 4: Tatkal NPS at Pension Yatra Camps
This is the headline channel right now. PFRDA’s Pension Yatra vans are touring districts across Delhi, Ahmedabad, Bengaluru and Kolkata for 15 days after NPS Diwas, with 12 more yatras planned over the next six months. These camps open accounts on the spot — “Tatkal NPS” — with field teams helping you fill forms and make the first contribution. If a yatra van comes to your area, this is the easiest route of all.
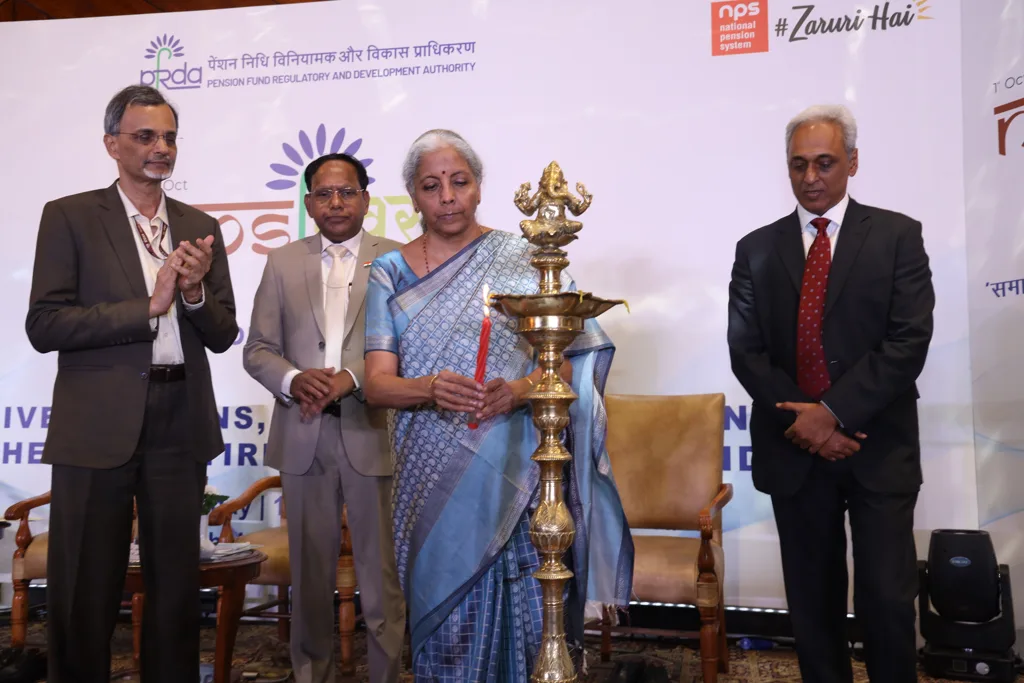
PFRDA’s NPS Diwas celebrations — NPS Sanchay was taken nationwide on NPS Diwas, October 1, 2026, alongside the Pension Yatra awareness drive.
Documents You’ll Need
| Document | Purpose |
|---|---|
| Aadhaar | Identity + e-KYC |
| PAN | Mandatory for NPS account opening |
| Bank account details | Contributions and eventual annuity payout |
| Passport-size photograph | Registration form (offline route) |
| Mobile number | OTP verification and PRAN alerts |
Practical tip: keep your mobile number the same one linked to your Aadhaar. Half the failed e-KYC attempts I hear about come down to a changed number nobody updated.
NPS Sanchay Interest Rate: The Honest Answer
Let me be straight with you: NPS Sanchay has no fixed interest rate. If someone — an agent, a YouTube video, a WhatsApp forward — promises you “X% fixed return on NPS Sanchay”, walk away. It’s a market-linked product, not a fixed deposit.
Your money is invested in a predefined pattern that mirrors the government-sector NPS pattern: 75% in government securities and corporate bonds, 25% in equity. Returns depend on how those markets do. NPS as a product has a long track record — the equity-heavy and government-bond portions of NPS have delivered healthy long-term compounding over the years — but past performance never guarantees future returns, and your corpus can fluctuate.
Here’s how to think about it honestly. The 75% debt portion gives the default pattern a conservative tilt, which suits the target audience: first-time savers who would panic at sharp swings. The 25% equity portion is the growth engine that, over 20-30 years, historically lifts the overall return above what pure fixed-income products offer. If you later understand investing better, you can switch to the regular NPS asset allocation choices — the PFRDA circular explicitly gives Sanchay subscribers the option to change the pension fund and asset allocation under the All Citizen norms.
The real “interest rate” advantage of NPS Sanchay isn’t a number — it’s the habit. ₹250 a month from age 25, compounding for 35 years, beats a 9% fixed product that someone never opened because the paperwork scared them off.
NPS Sanchay vs NPS: What’s Actually Different?
A common confusion: is Sanchay a separate scheme or just a simpler NPS account? It’s the latter. Sanchay runs on the same NPS rails, under the same regulator, with the same exit and tax rules. What changes is the front door. Here’s the comparison:
| Feature | NPS Sanchay | Regular NPS (All Citizen) |
|---|---|---|
| Minimum to open | ₹250 | ₹250 (revised from Oct 1, 2026) |
| Subsequent contribution minimum | ₹10 | ₹10 (revised from Oct 1, 2026) |
| Mandatory annual contribution | None | None (revised from Oct 1, 2026) |
| Investment choice at opening | No choice — predefined default pattern | Must choose active/auto allocation, equity %, pension fund |
| Default investment pattern | Mirrors govt-sector NPS (75% G-Sec + corporate bonds, 25% equity) | As chosen by subscriber |
| Entry age | 18–85 years | 18–70 years (entry) |
| Target audience | Informal workers, first-time savers | All citizens comfortable choosing allocations |
| Exit & withdrawal rules | Same NPS Regulations, 2015 | NPS Regulations, 2015 |
| Tax benefits | 80CCD(1), 80CCD(1B) — same | 80CCD(1), 80CCD(1B) |
| Charges | Same as NPS common schemes | As per PoP/PFRDA norms |
| Can change allocation later? | Yes — per All Citizen norms | Yes |
My honest take: if you’re comfortable with investment choices, the regular NPS gives you more control and a higher entry age ceiling isn’t a factor for most people under 70. If the choice screen is the reason you never opened an NPS account, Sanchay is the better door — you can always customize the allocation later. For the full picture of the regular product, see my National Pension System (NPS) guide.
NPS Sanchay vs NPS vs APY: Kaunsa Better Hai?
The Atal Pension Yojana (APY) is the product most readers will compare Sanchay with, since APY also targets the unorganized sector. Here’s how all three stack up:
| Feature | NPS Sanchay | Regular NPS | Atal Pension Yojana (APY) |
|---|---|---|---|
| Entry age | 18–85 years | 18–70 years | 18–40 years |
| Minimum contribution | ₹250 to open, ₹10 after | ₹250 to open, ₹10 after | ₹42/month onwards (depends on age and pension slab) |
| Mandatory annual contribution | None | None | Fixed monthly auto-debit — missing payments attracts penalties |
| Pension type | Market-linked (not guaranteed) | Market-linked (not guaranteed) | Guaranteed ₹1,000–₹5,000/month from age 60 |
| Investment choice | Predefined default (no choice at start) | Subscriber chooses allocation | Government-managed, no choice |
| Growth potential | Higher long-term potential (equity exposure) | Higher long-term potential | Fixed slabs — no upside beyond guaranteed pension |
| Flexibility | Contribute any amount, anytime | Contribute any amount, anytime | Fixed amount debited monthly |
| Tax benefit on contribution | 80CCD(1) + 80CCD(1B) ₹50,000 extra | 80CCD(1) + 80CCD(1B) ₹50,000 extra | 80CCD(1) only (no 80CCD(1B)) |
| Best for | Informal workers wanting a simple, flexible pension | Anyone wanting control over investments | Workers wanting a guaranteed fixed pension amount |
The honest way to choose: if you need a guaranteed monthly amount and you’re between 18 and 40, APY’s promise of up to ₹5,000/month is unbeatable for peace of mind. If you’re above 40, or your income is irregular and you can’t commit to a fixed monthly debit, NPS Sanchay is the practical choice — it accepts whatever you can put in, whenever you can. And if you’re salaried with EPF already running, the NPS tax deduction pairs well with it; I explain how the two interact in my EPF withdrawal guide context for salaried readers balancing both.
NPS Sanchay Withdrawal Rules: Paisa Kab Nikal Sakte Ho?
Withdrawal and exit rules for NPS Sanchay are identical to regular NPS — they follow the PFRDA (Exits and Withdrawals under the National Pension System) Regulations, 2015. This is a pension product, so the money is meant to stay invested until retirement, but the rules do give you doors:
- Normal exit at 60: You must use at least 40% of the corpus to buy an annuity (this becomes your monthly pension). You can take up to 60% as a tax-free lump sum.
- Full withdrawal for small corpus: Under PFRDA’s revised thresholds, if your total corpus is ₹5 lakh or less at exit, you can withdraw the entire amount — no mandatory annuity. This matters enormously for Sanchay’s audience, because many small savers will retire with exactly these kinds of corpus sizes.
- Premature exit (before 60): Allowed after 5 years of contributions. The annuity requirement is steeper here — 80% of the corpus must go into an annuity, with only 20% available as a lump sum.
- Partial withdrawal: After 3 years, you can withdraw up to 25% of your own contributions for specified needs — children’s education or marriage, buying a house, or medical treatment. Maximum three such withdrawals over the account’s life, with at least 5 years between them.
- On death of subscriber: The entire corpus is paid to the nominee or legal heir.
The ₹5 lakh full-withdrawal threshold is the single most Sanchay-relevant detail in the rulebook. A vendor who puts away ₹500 a month for 20 years will likely land under that line — meaning at 60, she can simply take the whole corpus home instead of being forced to buy an annuity she doesn’t understand.
Charges in NPS Sanchay: Kitna Kat-ta Hai?
Charges follow the same framework as the NPS common schemes, revised by PFRDA with effect from October 1, 2026:
- Onboarding fee: ₹200 one-time when you open through a PoP (bank/agent), collected as ₹50 per quarter through unit cancellation. Fully digital, non-face-to-face onboarding costs ₹100. GST extra on both.
- Annual PoP charge: 0.20% per annum of your assets under management, adjusted through the NAV and paid quarterly. On a ₹5 lakh corpus, that’s roughly ₹1,000 a year.
- Relief for digital users: If you opened through e-NPS and keep contributing through e-NPS or D-Remit, you don’t pay PoP charges at all.
- Dormant accounts: Defined as accounts with no contribution for four consecutive quarters after a contribution quarter — these don’t attract PoP charges.
Even with these charges, NPS remains one of the cheapest retirement products in India — fund management costs are a fraction of what mutual funds charge. For a ₹250-contribution saver, the percentage drag is tiny in absolute rupees.
Tax Benefits of NPS Sanchay
Because Sanchay is an NPS account, it carries the full NPS tax toolkit:
- Section 80CCD(1): Contributions up to ₹1.5 lakh a year deductible within the overall 80C ceiling.
- Section 80CCD(1B): An additional ₹50,000 deduction over and above the 80C limit — this one is exclusive to NPS (including Sanchay) and is the headline tax reason to prefer it over most other options.
- At exit: The 60% lump sum withdrawal is tax-free; the annuity pension you receive monthly is taxed as income.
Note: these deductions apply under the old tax regime. If you file under the new regime, most of these deductions don’t apply — check which regime suits you before counting on the tax benefit.
How Much Pension Can ₹250 a Month Actually Build?
Let’s do honest maths, not marketing maths. NPS returns are market-linked, so I’ll show an illustrative projection at a 10% assumed annual return — the actual result will differ. These numbers exist to show you the power of starting early, not to promise anything:
| Monthly Contribution | Start Age → 60 | Illustrative Corpus (10% p.a.) | Rough Monthly Pension* |
|---|---|---|---|
| ₹250 | 18 → 60 (42 years) | ~₹19.8 lakh | ~₹9,900 |
| ₹500 | 25 → 60 (35 years) | ~₹19.2 lakh | ~₹9,600 |
| ₹1,000 | 30 → 60 (30 years) | ~₹22.8 lakh | ~₹11,400 |
| ₹2,000 | 35 → 60 (25 years) | ~₹26.6 lakh | ~₹13,300 |
*Pension estimated assuming the full corpus buys an annuity at ~6% per annum. Illustrative only — actual returns and annuity rates will vary. NPS returns are not guaranteed.
The takeaway that matters: an 18-year-old putting away just ₹250 a month — less than the cost of two movie tickets — can build a corpus near ₹20 lakh. The first few years of compounding do the heaviest lifting. This is why PFRDA is chasing young informal workers with the Pension Yatra instead of waiting for them to turn 40.
Who Should Open an NPS Sanchay Account?
NPS Sanchay isn’t for everyone, and I’d rather say that plainly than pretend otherwise. It fits best if you check one or more of these boxes:
It’s not the best fit if you’re salaried with EPF + a regular NPS already running (you’ve got the product — Sanchay adds nothing), or if what you want is a guaranteed fixed monthly pension between 18-40 (APY does that job better). And if you’re saving for a daughter’s future rather than your own retirement, my Sukanya Samriddhi Yojana guide covers the dedicated scheme for that goal.
FAQs: NPS Sanchay
1. NPS Sanchay kya hai aur ye regular NPS se alag kaise hai?
NPS Sanchay PFRDA ka simplified NPS variant hai jo informal workers aur first-time savers ke liye banaya gaya hai. Regular NPS me aapko pension fund, active/auto allocation aur equity percentage khud choose karna padta hai; Sanchay me ye sab predefined default pattern (75% govt securities + corporate bonds, 25% equity) me automatically set hota hai. Exit rules, charges aur tax benefits dono me same hain — alag sirf shuruaat ki simplicity hai.
2. NPS Sanchay me minimum kitna invest karna padta hai?
Account kholne ke liye minimum ₹250 ka first contribution chahiye. Uske baad aap ₹10 se bhi contribute kar sakte hain. Koi mandatory yearly minimum nahi hai — chaaho to kuch mahine skip bhi kar sakte ho, account freeze nahi hoga.
3. NPS Sanchay ki age limit kya hai?
18 se 85 saal tak ke Indian citizens account khol sakte hain. Normal exit age 60 hai, jahan 40% corpus se annuity (monthly pension) leni hoti hai aur 60% lump sum mil sakta hai. Agar corpus ₹5 lakh ya usse kam hai to poora paisa ek saath nikal sakte hain.
4. Kya NPS Sanchay me fixed interest rate milta hai?
Nahi. NPS Sanchay market-linked product hai — isme koi fixed interest rate nahi hota. Paisa 75% government securities + corporate bonds aur 25% equity me lagta hai, isliye returns market performance par depend karte hain. Fixed return ka vaada karne wale se saavdhaan rahen.
5. NPS Sanchay account kaise kholen?
Paanch tareeke hain: (1) e-NPS portal se online, (2) kisi bhi NPS Point of Presence bank se, (3) najdeeki Common Service Centre (CSC) se, (4) Pension Yatra camps me Tatkal NPS se on-the-spot, (5) PFRDA ke digital channels se. Documents me Aadhaar, PAN, bank account details aur mobile number chahiye. Online kholne par PoP charges bhi nahi lagte.
6. NPS Sanchay aur APY me se kaunsa better hai?
Guaranteed fixed pension chahiye aur age 18-40 ke beech hai to APY (₹1,000-₹5,000/month guaranteed) behtar hai. Lekin income irregular hai, age 40 se upar hai, ya fixed monthly debit ka commitment nahi kar sakte — to NPS Sanchay zyada practical hai, kyunki isme koi yearly minimum nahi aur contribution kabhi bhi, kitna bhi kar sakte hain. Sanchay me long-term growth potential bhi zyada hai (equity exposure ki wajah se), jabki returns guaranteed nahi hain.
Final Words
NPS Sanchay won’t make headlines the way a tax cut does, but for the 90% of India’s workforce in the informal sector, it’s quietly one of the most important financial products launched this decade. ₹250 to open, ₹10 to continue, no yearly target, no investment exam at the door — PFRDA has finally built a pension product that meets small savers where they actually are.
My advice is simple: if nobody is saving for your retirement — no employer, no PF, no pension — then that somebody has to be you, and Sanchay is the easiest first step available right now. Open the account through e-NPS or your nearest CSC this week, set whatever monthly amount you can manage without stress, and let compounding do the quiet work. Your 60-year-old self will thank you for a decision your 25-year-old self made in ten minutes.
Want the full picture of the underlying product before you decide? Read my complete National Pension System (NPS) guide next — it covers everything Sanchay inherits, from fund managers to annuity options, in detail.
📖 Related: Atal Pension Yojana — government pension options ke baare me padhein.