
A farmer in Maharashtra needs ₹80,000 for seeds and fertilizer in June. A moneylender offers it at 36% per year. A bank, through the Kisan Credit Card, offers the same money at an effective interest of just 4% per year — if repaid on time. That single difference is why the Kisan Credit Card (KCC) remains the most important farm-credit scheme in India, nearly three decades after it launched.
✅ Verified information: This guide is based on the RBI’s Modified Interest Subvention Scheme circular for FY 2025-26, bank KCC pages, and PIB releases. Interest rates, limits, and eligibility stated here match official sources. Last verified: October 15, 2026.
What Is the Kisan Credit Card Scheme?
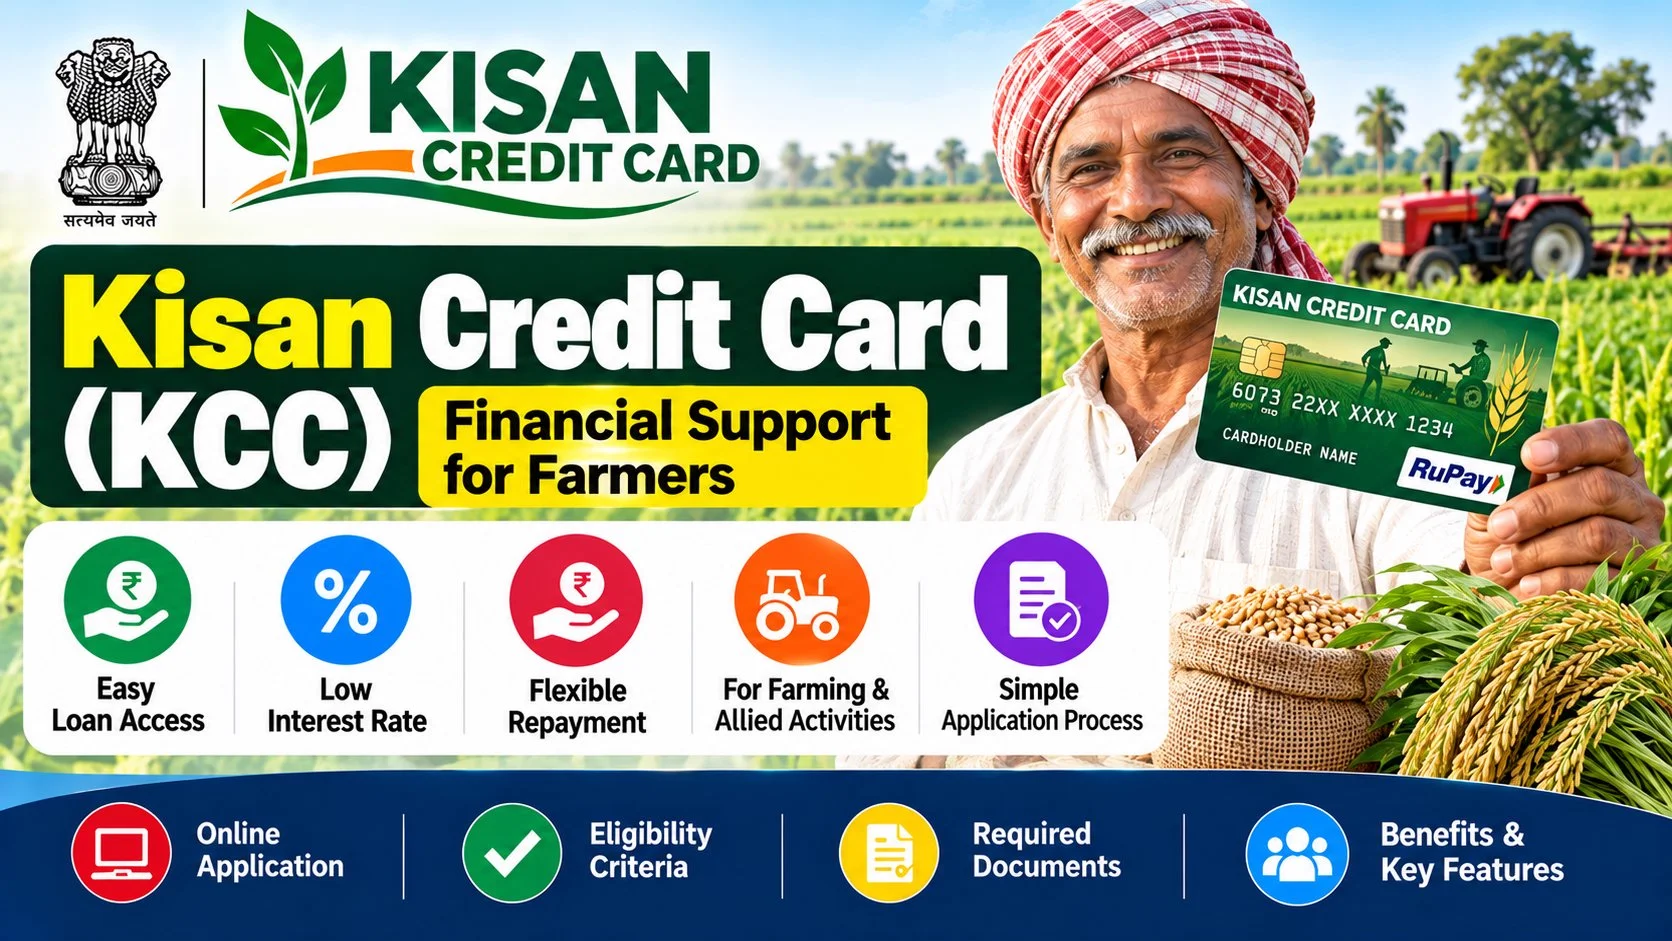
The Kisan Credit Card is a government-backed credit facility that gives farmers a revolving credit limit for crop cultivation, post-harvest expenses, farm maintenance, household needs, and allied activities like dairy, poultry, and fisheries. It was introduced in 1998 on the recommendation of the R. V. Gupta Committee, with the scheme model prepared by NABARD.
The core idea was simple: farmers face a timing gap. They spend on inputs months before they earn from the harvest. Before KCC, that gap was filled by moneylenders charging 24% to 60% a year. KCC brought farmers into the formal banking system with one card, one limit, and interest as low as 4%.
Today there are roughly 7 crore active KCC accounts in India, issued through public sector banks, private banks (rural and semi-urban branches), Regional Rural Banks, Small Finance Banks, and cooperative banks.
Kisan Credit Card: Key Facts at a Glance
| Detail | Information |
|---|---|
| Scheme name | Kisan Credit Card (KCC) |
| Launched | 1998 (R. V. Gupta Committee recommendation) |
| Run by | Banks under RBI/NABARD guidelines; interest subvention by Government of India |
| Interest rate | 7% per year; effective 4% on prompt repayment |
| Subvention cap | Up to ₹3 lakh per farmer per year (FY 2025-26) |
| Collateral-free limit | Up to ₹2 lakh |
| Validity | 5 years, with annual review |
| Who can apply | Owner cultivators, tenant farmers, sharecroppers, SHGs/JLGs, dairy/fisheries farmers |
Kisan Credit Card Interest Rate Explained: How 7% Becomes 4%
This is the part most articles explain badly, so let’s do it properly. The KCC interest benefit works in two layers under the Modified Interest Subvention Scheme (MISS).
Layer 1: The 7% concessional rate
Banks lend short-term crop loans through KCC at 7% per year. The government pays an interest subvention of 1.5% directly to the lending bank (for FY 2025-26), which is what makes the 7% rate possible for the farmer. This applies to short-term crop loans and short-term loans for allied activities (animal husbandry, dairy, fisheries, bee-keeping) up to an overall limit of ₹3 lakh per farmer per year.
Layer 2: The 3% prompt repayment incentive
If you repay the loan within one year of disbursement (or by the due date fixed by the bank, whichever is earlier), you get an additional 3% interest subvention. That brings your effective rate down to 4% per year.
A worked example: You take a ₹2,00,000 crop loan on June 1 for the kharif season at 7%. You repay the full amount on March 15, within the one-year window. The 3% prompt repayment incentive applies, so your effective interest for the period is roughly 4% per year — about ₹6,200 on the amount for 9.5 months instead of roughly ₹10,800 at 7%. Miss the one-year window, and the incentive is gone: you pay the full 7%.
What happens above ₹3 lakh?
The subvention and the prompt repayment incentive apply only up to ₹3 lakh per farmer per year. If you borrow ₹4,00,000, the first ₹3,00,000 gets the 7%/4% treatment, and the remaining ₹1,00,000 is charged at the bank’s normal lending rate. Priority is given to crop loans; whatever remains of the limit can go to allied activities.
| Situation | Interest you pay |
|---|---|
| Loan up to ₹3 lakh, repaid within 1 year | 4% per year (7% minus 3% prompt repayment incentive) |
| Loan up to ₹3 lakh, repaid after 1 year | 7% per year (incentive not available) |
| Amount above ₹3 lakh | Bank’s normal lending rate (no subvention) |
| Allied activities only (dairy/fisheries) | Subvention available up to ₹2 lakh sub-limit |
Note on the ₹5 lakh figure: The Union Budget 2025-26 announced raising the KCC loan limit under the Modified Interest Subvention Scheme from ₹3 lakh to ₹5 lakh. The RBI’s operative circular for FY 2025-26, however, continues the subvention cap at ₹3 lakh per farmer. Until banks formally implement the higher limit, treat ₹3 lakh as the subvention ceiling and confirm the current limit with your bank before applying.
How Much Loan Can You Get? KCC Limit Calculation
Your KCC limit is not a flat number for everyone. The bank fixes it based on:
- Scale of finance for your crop (the per-acre cost of cultivation set for your district)
- Area cultivated — your landholding or leased area
- Cropping pattern — single crop or multiple crops per year
- Allied activities — dairy, poultry, fisheries add to the limit
- Household and maintenance needs — a component is included for these
The limit is typically enhanced by about 10% each year on renewal, subject to satisfactory repayment and review. Collateral (land mortgage or other security) is not required for loans up to ₹2 lakh — this threshold was raised from ₹1.6 lakh effective January 2025.
KCC vs Regular Agricultural Loan: What’s the Difference?
| Feature | Kisan Credit Card | Regular agri loan |
|---|---|---|
| Interest rate | 7%, effective 4% on prompt repayment | Usually 9–12%, no subvention |
| Withdrawals | Revolving — withdraw and repay as needed | One-time disbursement |
| Validity | 5 years with annual review | Single loan tenure |
| Collateral | Not needed up to ₹2 lakh | Usually required |
| Card facility | RuPay KCC debit card for ATM/PoS/UPI | No card |
| Insurance | Crop insurance linkage, accident cover | Not bundled |
Benefits of Kisan Credit Card
1. Cheapest farm credit available. At an effective 4%, KCC is cheaper than any personal loan, gold loan, or moneylender advance a farmer can access.
2. Revolving credit. You don’t reapply every season. Within your sanctioned limit, you withdraw when you need money and repay after harvest. The limit stays valid for 5 years.
3. Covers more than crops. Since 2018-19, KCC covers animal husbandry and fisheries too. Dairy farmers, poultry keepers, and fish farmers can all get KCC.
4. RuPay KCC debit card. Withdraw cash at ATMs, pay at shops, and use UPI — the card works like a normal debit card linked to your KCC limit.
5. Insurance bundled in. KCC borrowers are covered under crop insurance (PMFBY linkage) and get personal accident insurance cover.
6. Post-harvest flexibility. Small and marginal farmers can get interest subvention for up to six months after harvest on loans against negotiable warehouse receipts — so you aren’t forced into distress sales.
7. Relief in natural calamities. If crops are damaged by drought, flood, or other notified calamities, the subvention continues on restructured loans (first year; up to three years for severe calamities), with the prompt repayment incentive also available in such cases.
8. Single-window simplicity. One application, one limit, one card — instead of separate loans for seeds, equipment, and consumption needs.
Who Can Apply? KCC Eligibility
- Individual farmers who own and cultivate land
- Joint borrowers (two or more farmers together)
- Tenant farmers, sharecroppers, and oral lessees with valid lease or self-declaration
- Self-Help Groups (SHGs) and Joint Liability Groups (JLGs) of farmers
- Farmers in allied activities: dairy, poultry, animal husbandry, fisheries, bee-keeping
- PM-KISAN beneficiaries — eligible for a simplified, fast-track KCC
Applicants are generally expected to be between 18 and 75 years of age. Borrowers with uncleared defaulted loans (NPAs) at banks are not eligible until dues are settled.
Documents Required for Kisan Credit Card
| Document | Details |
|---|---|
| Identity proof | Aadhaar card (mandatory for e-KYC) |
| Address proof | Aadhaar / voter ID / utility bill |
| Land proof | Khasra/khatauni or updated land records; lease agreement for tenants |
| Bank details | Existing savings account passbook (if any) |
| Photographs | 2 recent passport-size photos |
| Mobile number | Linked with Aadhaar for OTP verification |
PM-KISAN beneficiaries get a simplified one-page form — the bank pre-fills details from PM-KISAN records, so the process is faster.
How to Apply for Kisan Credit Card Online: Step-by-Step
There is no single central KCC website for applications — you apply through your bank. Most public sector banks (SBI, Bank of Baroda, PNB, Canara Bank) and many RRBs accept KCC applications on their websites. PM-KISAN beneficiaries can also use the KCC module linked with pmkisan.gov.in.
Step 1: Go to your bank’s official website and find the “Kisan Credit Card” or “Agriculture Loans” section.
Step 2: Click “Apply Online” and choose KCC from the loan options.
Step 3: Fill in personal details — name, Aadhaar number, mobile number, address.
Step 4: Enter land and crop details — survey numbers, area in acres, crops you grow.
Step 5: Enter the loan amount required and select your nearest branch.
Step 6: Upload or keep ready scanned copies of Aadhaar, land records, and photograph.
Step 7: Submit the form and note the application reference number.
Step 8: The bank verifies your details and land records, usually contacting you within 3–4 working days. On approval, the KCC is typically issued within about 15 days of a complete application.
How to Apply Offline (Branch or CSC)
If online application feels difficult, visit your nearest bank branch or Common Service Center (CSC):
- Ask for the KCC application form (PM-KISAN beneficiaries get the simplified one-page version).
- Fill in personal, land, and crop details carefully — wrong survey numbers are the most common cause of rejection.
- Attach Aadhaar, land records, photos, and bank passbook copy.
- Submit at the branch and take the acknowledgement receipt with the reference number.
- The bank does field verification of land and crops, then sanctions the limit and issues the RuPay KCC card.
RuPay Kisan Credit Card: How the Card Works
Once your KCC is sanctioned, the bank issues a RuPay debit card linked to your KCC account. You can:
- Withdraw cash from any ATM up to your sanctioned limit
- Pay directly at fertilizer, seed, and equipment dealers via PoS
- Use UPI linked to the KCC account
Interest is charged only on the amount you actually withdraw, not on the full sanctioned limit. Repay after harvest, and the limit is available again — that’s the revolving facility.
KCC for Dairy, Poultry, and Fisheries
Many farmers don’t know KCC isn’t only for crops. If you’re in allied activities:
- You can get KCC for dairy (milk animals), poultry, sheep/goat rearing, piggery, and fisheries.
- The interest subvention benefit for exclusively allied-activity loans applies up to ₹2 lakh per farmer.
- Working capital needs — feed, veterinary care, fingerlings, nets — are covered.
- The same 7% → 4% structure applies on prompt repayment.
This is especially useful because dairy and fishery income is monthly, making the one-year prompt repayment window easy to meet.
Repayment and Renewal: How to Keep Your KCC Active
Repayment: Repay within the crop season or within one year of withdrawal to keep the 3% incentive. Most farmers repay right after selling the harvest.
Annual review: The bank reviews your KCC every year. With a clean repayment record, the limit is usually enhanced by about 10%.
Renewal: The card is valid for 5 years. Renewal is a simple process at the branch — updated land records and a fresh application are usually enough if repayments have been regular.
What if you can’t repay on time? Talk to the bank before the due date. In case of crop failure from notified natural calamities, banks can restructure the loan with continued subvention rather than marking it as default.
Ghar-Ghar KCC: The Saturation Drive and Kisan Rin Portal
In 2023, the government launched the “Ghar-Ghar KCC Abhiyaan” — a saturation drive to ensure every PM-KISAN beneficiary who was eligible also got a Kisan Credit Card. Camps were held at village level where farmers could fill the simplified one-page form on the spot. If you are a PM-KISAN beneficiary and never got a KCC, ask at your bank branch whether the simplified form is still being accepted — in most banks, it is.
Behind the scenes, KCC lending is now monitored through the Kisan Rin Portal (fasalrin.gov.in). Banks upload KCC data to this portal, which helps the government track interest subvention claims and spot regional gaps in farm credit. You don’t need to register on this portal as a farmer — it’s a monitoring system for banks and the government — but knowing it exists explains why banks now ask for Aadhaar-seeded, complete applications: the data has to match at the national level.
Crop Insurance With KCC
KCC borrowers are linked to crop insurance under the Pradhan Mantri Fasal Bima Yojana (PMFBY). Premium is deducted from the KCC account, and claims in case of crop loss are credited to the same account. In addition, KCC holders get personal accident insurance coverage. Ask your bank for the exact cover amounts at the time of sanction, since they vary by bank.
5 Mistakes That Get KCC Applications Rejected
1. Outdated land records. If your khasra/khatauni doesn’t show you as the cultivator, the bank can’t verify. Update records at the tehsil first.
2. Name mismatch. The name on your Aadhaar, land records, and bank account must match. Even a spelling difference causes delays.
3. Existing default. An uncleared overdue farm loan at any bank blocks a new KCC. Settle or restructure it first.
4. Inflated loan demand. Asking for far more than your scale of finance allows raises red flags. The bank calculates the eligible limit anyway.
5. Ignoring the bank’s calls. Field verification needs your presence or a response. Miss it, and the file goes cold.
Frequently Asked Questions
kisan credit card kaise banaye?
Apply through your bank’s website, nearest branch, or CSC with Aadhaar, land records, photos, and bank details. The bank verifies and issues the card, usually within about 15 days of a complete application.
What is the Kisan Credit Card interest rate?
7% per year on loans up to ₹3 lakh. If you repay within one year, an additional 3% incentive brings the effective rate to 4% per year.
kcc me kitna loan milta hai?
The limit depends on your crop, land area, and scale of finance. Interest subvention applies up to ₹3 lakh per year; loans up to ₹2 lakh need no collateral.
Can tenant farmers get KCC?
Yes. Tenant farmers, sharecroppers, and oral lessees are eligible with a valid lease agreement or self-declaration.
How do I check my KCC application status?
Use the reference number from your application on your bank’s loan-status page, call the bank’s customer care, or visit the branch. There is no single central status portal — status is tracked bank-wise.
Is KCC available for dairy and fisheries?
Yes. Since 2018-19, KCC covers animal husbandry, dairy, poultry, and fisheries, with interest subvention on allied-activity loans up to ₹2 lakh.
🔗 Related Government Schemes
Final Word
The Kisan Credit Card is the cheapest formal credit a farmer can get in India — 4% effective interest against 36% from a moneylender is not a small gap, it’s the difference between profit and a debt trap. If you farm, keep livestock, or run a fishery, and you don’t have a KCC yet, the application costs nothing and the card stays valid for five years. Apply through your bank, keep your land records updated, and repay on time to keep the 4% rate working for you every single season.