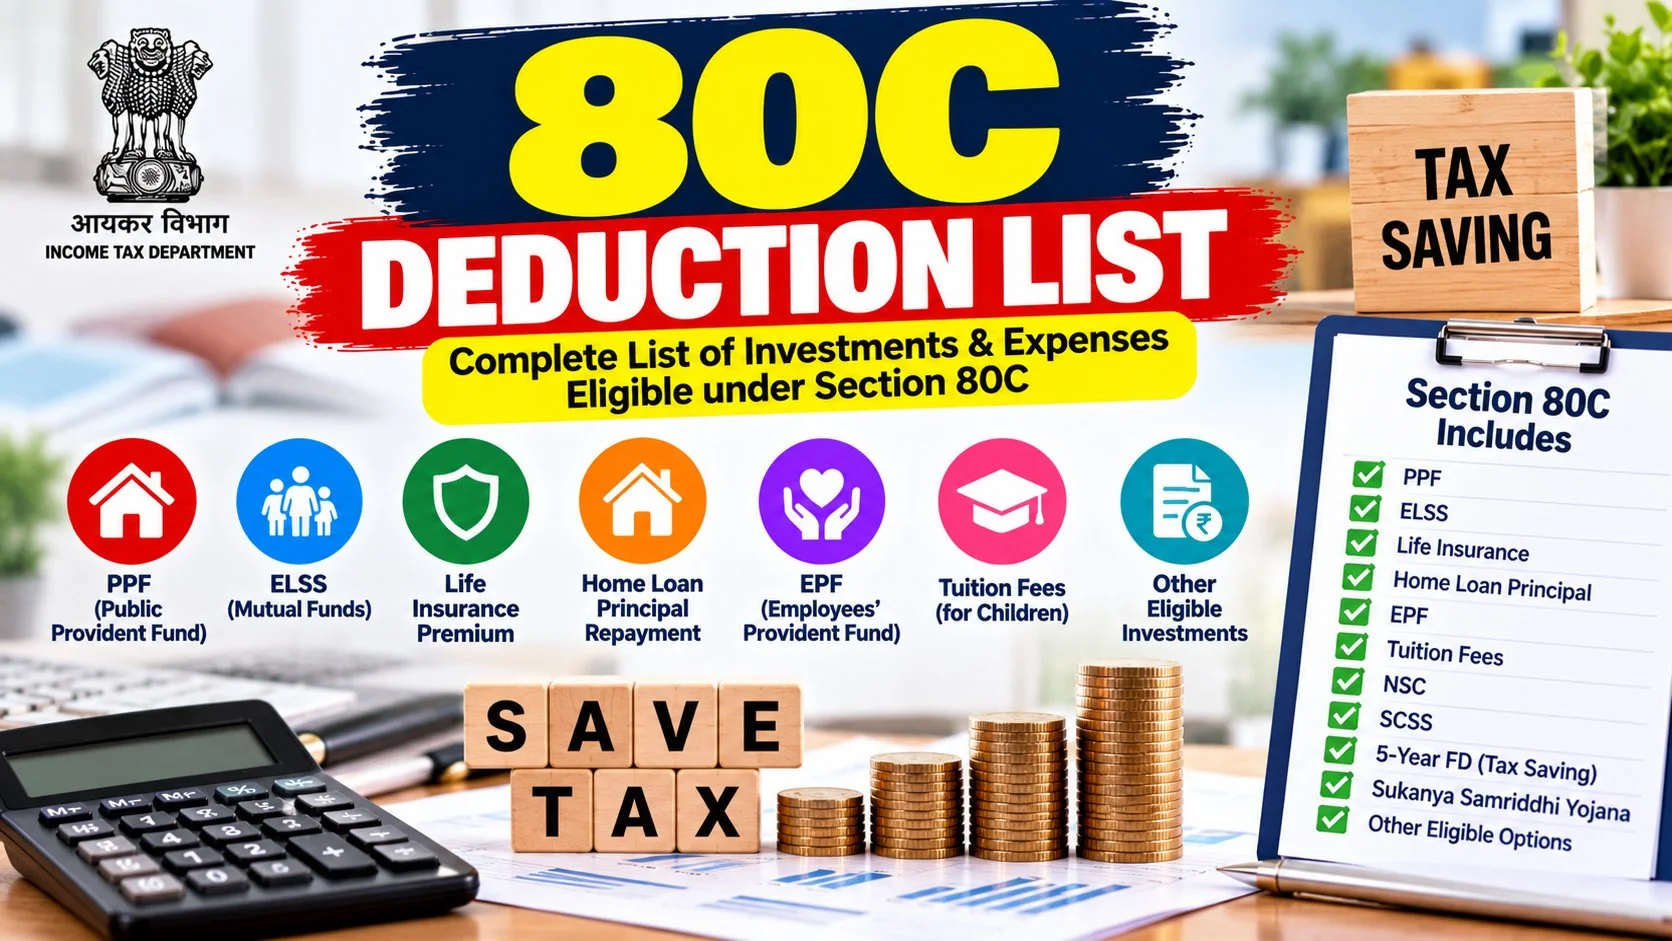

Every February, the same question pops up in offices across India: “80C me aur kitna bacha sakte ho?” If you are staring at the 80C deduction list wondering which investments actually qualify, how much you can claim, and whether it even matters under the new tax regime — this guide has every answer, with the exact limits.
✅ This guide is based on official government sources and notifications. Last verified: October 12, 2026. Scheme details, eligibility criteria, and benefit amounts are revised by the government from time to time — always cross-check the latest information on the official portal before applying.
Section 80C of the Income Tax Act is the most popular tax-saving section in India — and also the most misunderstood. People invest randomly in March, buy policies they do not need, and still end up paying more tax than necessary. Let us fix that with a complete, honest breakdown.
80C Deduction: The Essentials
| Particular | Detail |
|---|---|
| Section | 80C of Income Tax Act, 1961 |
| Maximum deduction | ₹1,50,000 per financial year |
| Available in | Old tax regime only |
| Who can claim | Individuals and HUFs |
| Combined limit note | 80C + 80CCC + 80CCD(1) together capped at ₹1.5 lakh |
The single most important line in that table: 80C works only in the old tax regime. The Income Tax Department notifies these provisions officially. If you opted for the new regime, none of these deductions apply. Confused about which regime suits you? Read our new vs old tax regime comparison first.
Complete 80C Deduction List with Limits
Here is every major eligible investment and expense under Section 80C:
| Investment / Expense | Type | Lock-in | Returns* |
|---|---|---|---|
| PPF (Public Provident Fund) | Government scheme | 15 years | ~7.1% tax-free |
| EPF (Employee Provident Fund) | Salary deduction | Till retirement | ~8.25% tax-free |
| ELSS (Equity Linked Savings Scheme) | Mutual fund | 3 years | Market-linked |
| NSC (National Savings Certificate) | Post office | 5 years | ~7.7% |
| SCSS (Senior Citizen Savings Scheme) | Post office/bank | 5 years | ~8.2% |
| ULIP (Unit Linked Insurance Plan) | Insurance + investment | 5 years | Market-linked |
| Life insurance premium | Insurance | Policy term | As per policy |
| Home loan principal | Loan repayment | — | — |
| Tuition fees (2 children max) | Expense | — | — |
| Sukanya Samriddhi Yojana | Government scheme | 21 years / girl turns 18 | ~8.2% tax-free |
| Tax-saving FD (5-year) | Bank deposit | 5 years | ~7% taxable |
| NPS (Tier 1, 80CCD(1)) | Pension | Till age 60 | Market-linked |
*Interest rates as notified; check current rates before investing. Our Sukanya Samriddhi Yojana guide and NPS guide cover those schemes in depth, and the Sukanya Samriddhi Yojana calculator shows what an SSY deposit grows into by maturity.
80C for Salaried Employees: What Gets Auto-Counted
If you are salaried, a big chunk of your 80C may already be done without you doing anything:
- EPF contribution: Your 12% of basic + DA goes to EPF automatically. For someone with ₹50,000 monthly basic, that is ₹72,000/year already in 80C.
- Life insurance premium: If your employer deducts group insurance premium, it counts.
- Home loan principal: Your EMI’s principal component counts (get the certificate from your lender).
- Tuition fees: School/college fees for up to 2 children (receipts needed).
Before investing a single rupee in March, add up these four. Many salaried people discover they only need ₹30,000-50,000 more to hit the ₹1.5 lakh cap.
80C Deduction for HUF
Hindu Undivided Families can also claim 80C on investments made from HUF funds — PPF in the HUF’s name, life insurance on members’ lives, ELSS, NSC, and so on. The ₹1.5 lakh limit applies separately to the HUF, over and above the individual members’ limits. This is a legitimate way for families to double up tax saving, but keep the accounting clean — HUF investments must come from HUF income, not personal funds routed through.
80C vs 80CCD vs 80D: Do Not Mix Them Up
| Section | Covers | Limit | Extra Benefit? |
|---|---|---|---|
| 80C | PPF, ELSS, EPF, NSC, insurance, etc. | ₹1.5 lakh | — |
| 80CCD(1B) | NPS additional | ₹50,000 | Over and above 80C |
| 80D | Health insurance premium | ₹25K (self) / ₹50K (senior citizen parents) | Separate from 80C |
| 80TTA / 80TTB | Savings/FD interest | ₹10K / ₹50K (seniors) | Separate from 80C |
The NPS 80CCD(1B) deduction is the hidden gem: an extra ₹50,000 over and above your ₹1.5 lakh 80C limit. If you are in the 30% bracket, that is ₹15,600 in tax saved for a ₹50,000 NPS investment.
Best 80C Options Compared: Where Should YOUR Money Go?
Not all 80C options are equal. Here is an honest comparison:
If you want maximum safety: PPF + EPF
Government-backed, tax-free returns, but long lock-ins. Best for the risk-averse core of your portfolio.
If you want maximum growth: ELSS
Shortest lock-in (3 years) among 80C options and equity-linked growth potential. But market risk is real — do not put emergency money here.
If you have a daughter under 10: SSY
8.2% tax-free (SSY rate confirmed at 8.2% for the Oct-Dec 2026 quarter) with the highest safe return in the 80C basket. Our SSY guide has the full calculation.
If you are already maxed on 80C: NPS 80CCD(1B)
The extra ₹50,000 deduction. Our NPS guide explains Tier 1 vs Tier 2.
What to avoid
Do not buy a ULIP or endowment policy purely for 80C in March panic. The commissions are high, returns are mediocre, and you are locked in for years. Buy insurance for protection, invest for growth — mixing the two usually gives you the worst of both.
How Much Tax Does 80C Actually Save You?
| Tax Slab (Old Regime) | Tax Saved on Full ₹1.5L 80C |
|---|---|
| 5% slab | ₹7,800* |
| 20% slab | ₹31,200* |
| 30% slab | ₹46,800* |
*Including 4% health and education cess. The higher your slab, the more every 80C rupee is worth.
80C in the New Tax Regime: The Hard Truth
Under the new regime, 80C deductions are not available. This is the trade-off for lower slab rates. Before you blindly continue 80C investments out of habit, do the math:
- Calculate tax under the new regime (no deductions).
- Calculate tax under the old regime (with your actual 80C + 80D + HRA).
- Pick the lower number. That is it.
Our new vs old tax regime article walks through this comparison with examples. And if you are doing HRA planning, our HRA calculation guide shows exactly how much exemption you can claim.
Proofs You Need to Submit (Old Regime)
Your employer will ask for investment proofs in January-February. Keep these ready:
- PPF passbook / statement showing deposits
- ELSS investment statements
- Life insurance premium receipts
- Home loan principal certificate from lender
- Tuition fee receipts (school/college)
- NSC certificates
- NPS Tier 1 contribution statement
- 5-year tax-saving FD receipt
Pro tip: do not wait till January. Invest monthly through the year (SIP in ELSS, monthly PPF deposits) instead of a lump sum in March. You get better averaging, less panic, and the same deduction.
Section 80C Sub-Sections Explained (80CCC, 80CCD)
80C does not work alone. Two sibling sections share its ₹1.5 lakh cap, and understanding them prevents double-counting mistakes:
Section 80CCC: Pension plans from insurers
Premiums paid towards annuity/pension plans from LIC or other insurers (like Jeevan Suraksha-type plans) qualify under 80CCC. The catch: 80CCC + 80C + 80CCD(1) together cannot exceed ₹1.5 lakh. So if you already max 80C with PPF and ELSS, an 80CCC pension premium gives you zero additional deduction.
Section 80CCD(1): NPS Tier 1 (within the cap)
Your NPS Tier 1 contributions up to 10% of salary (14% for government employees) qualify under 80CCD(1) — but again, inside the same ₹1.5 lakh umbrella. The real extra comes from 80CCD(1B): an additional ₹50,000 exclusively for NPS, outside the cap.
Section 80CCD(2): Employer NPS (no cap linkage)
Your employer’s NPS contribution (up to 10% of basic, 14% for govt) is deductible under 80CCD(2) with NO upper cap linkage to 80C. If your employer offers NPS, this is pure extra tax saving most people ignore.
Month-by-Month 80C Investment Plan (Instead of March Panic)
Here is a practical monthly plan for someone targeting the full ₹1.5 lakh:
| Month | Action | Amount |
|---|---|---|
| April | Start ELSS SIP | ₹5,000/month |
| April | PPF auto-debit setup | ₹5,000/month |
| May – March | EPF auto-deducted from salary | ~₹6,000/month |
| June | Pay life insurance annual premium | ₹25,000 (one-time) |
| July | NPS Tier 1 top-up (80CCD-1B) | ₹50,000 (one-time) |
| January | Submit proofs to employer | — |
Total: ELSS ₹60,000 + PPF ₹60,000 + EPF ~₹72,000 = already over ₹1.5 lakh before insurance. Adjust to your salary — the principle is the same: automate through the year.
80C Mistakes That Cost Real Money
Mistake 1: Investing without checking EPF first
A person earning ₹1 lakh/month with ₹12,000/month EPF already has ₹1.44 lakh in 80C. Investing another ₹1.5 lakh in ELSS “for tax saving” wastes the deduction — only ₹6,000 of it counts.
Mistake 2: Choosing the new regime but continuing 80C investments for “tax saving”
PPF and ELSS are still good investments on merit. But if you are in the new regime, do not choose them BECAUSE of 80C — the deduction does not exist there.
Mistake 3: Buying insurance-cum-investment in March
Endowment plans and ULIPs sold in the tax-saving rush have high first-year commissions (up to 30-40% in some traditional plans). A term plan + separate ELSS/PPF almost always beats them.
Mistake 4: Forgetting the NPS extra ₹50,000
Even people who max 80C often miss 80CCD(1B). It is the only “extra” deduction left in the old regime — use it.
Mistake 5: Not keeping proofs
No proof = no deduction at assessment. Digital copies in a dedicated folder (“FY25-26 Tax Proofs”) take 10 minutes to organize and save hours later.
80C and Home Loans: The Double Benefit
Home loan borrowers get two separate deductions that are often confused:
- Principal repayment → 80C (within ₹1.5 lakh cap, shared with PPF/ELSS/etc.)
- Interest payment → Section 24(b) (up to ₹2 lakh for self-occupied property, SEPARATE from 80C)
So a home loan EMI gives you deductions in two buckets. Get the interest/principal bifurcation certificate from your lender every year — it is the single most valuable tax document for homeowners.
80C for Different Life Stages
Age 25-30 (early career)
Prioritize ELSS (growth + shortest lock-in) and start PPF for the safe base. EPF is building automatically. Avoid locking too much in illiquid options.
Age 30-40 (family stage)
Add SSY if you have a daughter, term insurance for protection (premium counts in 80C), and home loan principal if you bought a house. NPS 80CCD(1B) becomes attractive in higher slabs.
Age 40-50 (peak earning)
Max everything: 80C full, NPS extra ₹50K, 80D for family floater + parents. This is when each deduction rupee saves the most tax (30% bracket).
Age 50+ (pre-retirement)
Shift toward SCSS (if eligible), PPF, and safe options. ELSS equity exposure should reduce as retirement nears — but do not stop 80C entirely while you still have taxable salary income.
How 80C Interacts with HRA and 80D
A complete old-regime tax plan stacks three independent buckets:
| Bucket | Max Deduction | Example |
|---|---|---|
| 80C (+80CCC+80CCD1) | ₹1,50,000 | EPF + PPF + ELSS |
| 80CCD(1B) NPS extra | ₹50,000 | NPS Tier 1 top-up |
| 80D health insurance | ₹25,000–₹1,00,000 | Self + parents (senior citizen) |
| HRA exemption (10/13A) | As per formula | See our HRA calculation guide |
| 24(b) home loan interest | ₹2,00,000 | Self-occupied property |
Stacked together, a well-planned old-regime filer can legitimately reduce taxable income by ₹5-6 lakh. That is the real power of understanding the full list — not just 80C in isolation.
Digital Proof Submission: What Employers Accept Now
Most large employers now accept digital proofs through HR portals. What typically works:
- PDF statements downloaded from AMC/bank portals (ELSS, PPF, NPS)
- Scanned premium receipts (life insurance)
- Form 16 from your previous employer (if you switched jobs)
- Lender’s provisional interest/principal certificate (home loan)
- School fee receipts with the child’s name
Screenshots of SMS confirmations usually do NOT count. Download the actual statement PDFs — it takes two minutes per investment and avoids back-and-forth with HR in February.
80C-Eligible Investments You Probably Did Not Know About
Beyond the famous options, these lesser-known entries also qualify:
- Stamp duty and registration: Paid on purchase of a residential house — claimable in the year of payment.
- Education loan? No — but tuition fees yes: Many confuse the two. Education loan INTEREST is 80E (separate, no cap). Tuition FEES are 80C.
- Deposits in Post Office Time Deposit (5-year): The 5-year POTD qualifies; shorter tenures do not.
- Subscription to notified bonds (NABARD etc.): When notified by the government, these qualify.
- Contribution to approved superannuation fund: If your employer maintains one, your contribution counts.
What Happens If You Exceed ₹1.5 Lakh in 80C?
Nothing bad — the excess is simply ignored for tax purposes. If you invest ₹2 lakh across PPF, ELSS, and EPF, you still claim only ₹1.5 lakh. The extra ₹50,000 earns returns normally but gives no additional deduction. This is why sequencing matters: once 80C is full, redirect further money to the NPS 80CCD(1B) bucket or non-80C goals instead of stuffing more into 80C options for “tax saving” that does not exist.
Carry Forward: Can Unused 80C Move to Next Year?
No. 80C is strictly use-it-or-lose-it per financial year. Unlike capital losses, unused deduction cannot be carried forward. This is exactly why March panic happens — but as shown above, monthly investing through the year is the calmer path to the same result.
80C vs Tax-Saving FD vs ELSS: A Decision Framework
When readers ask “which ONE should I pick,” here is the framework I suggest:
| Your Situation | Best Pick | Why |
|---|---|---|
| Conservative, want zero risk | PPF | Government-backed, tax-free, flexible deposits |
| Young, long horizon, want growth | ELSS via SIP | Equity upside, 3-year lock-in only |
| Have a daughter below 10 | SSY | Highest safe rate, built for her future |
| Already have EPF running | Top up with ELSS/PPF | Do not duplicate what salary already covers |
| In 30% bracket, 80C full | NPS (80CCD-1B) | Extra ₹50K deduction nowhere else available |
There is no single “best” 80C investment — only the best fit for your age, risk appetite, and what your salary already covers. The investors who do best are not the ones who pick the highest-return option; they are the ones who automate a sensible mix and never think about it in March.
FAQs: 80C Deduction List
What is the maximum 80C deduction limit?
₹1,50,000 per financial year, combining 80C + 80CCC + 80CCD(1). NPS gets an additional ₹50,000 under 80CCD(1B).
Is 80C available in the new tax regime?
No. 80C deductions apply only under the old tax regime. The new regime offers lower rates instead of deductions.
Can I claim 80C for my spouse’s PPF?
Yes, investments in your spouse’s or children’s PPF/ELSS/insurance qualify for YOUR 80C deduction, within your ₹1.5 lakh limit.
Does EPF employer contribution count in 80C?
Only your own (employee) contribution counts. The employer’s contribution is exempt separately up to limits and does not eat into your 80C cap.
Can tuition fees for more than 2 children be claimed?
No — tuition fee deduction under 80C is capped at 2 children, and covers tuition only (not donations, development fees, or transport).
Is stamp duty on house purchase eligible under 80C?
Yes, stamp duty and registration charges for a residential house purchase qualify under 80C, within the ₹1.5 lakh limit, in the year of payment.
Can I claim 80C without making any new investment?
80C needs actual investment or payment, but check what you already have before investing more. Your EPF deduction from salary, home loan principal repayment, children’s tuition fees, and LIC premiums you already pay often add up to 1.5 lakh on their own.
Can I claim 80C if I did not declare investments to my employer?
Yes. Declare and claim them while filing your ITR, as long as the investments were made before 31st March of the financial year. Your employer only controls TDS. The return is the final word.
ELSS or PPF, which is better under 80C?
ELSS suits long-term wealth creation with the shortest 80C lock-in of 3 years and market-linked returns, ideal if you are under 45 and comfortable with risk. PPF suits the safety-first portion with sovereign-backed tax-free returns over 15 years. Most balanced savers use both, ELSS for growth and PPF for stability.
Does the 1.5 lakh limit include NPS under 80CCD(1)?
Yes. Sections 80C, 80CCC, and 80CCD(1) share one combined 1.5 lakh ceiling under Section 80CCE. The extra 50,000 for NPS under 80CCD(1B) is separate and takes your total deduction to 2 lakh.
What is the 10x sum assured rule for life insurance under 80C?
For policies issued on or after 1st April 2012, the premium qualifies for 80C only if the sum assured is at least 10 times the annual premium. If the policy fails this test, only a proportionate part of the premium is deductible.
Which 80C option has the shortest lock-in?
ELSS at 3 years is the shortest. Next come 5-year tax-saving FDs, NSC, and SCSS at 5 years, while PPF locks money for 15 years. Match the lock-in to when you will actually need the money.
Is stamp duty on a resale flat eligible under 80C?
Yes. Stamp duty, registration fees, and other direct expenses on the purchase of a residential house, new or resale, qualify under 80C in the year of purchase. The property must not be sold within 5 years or the deduction gets reversed.
Can NRIs claim 80C deductions?
Yes. NRIs can claim 80C for eligible investments made in India: PPF in existing accounts, ELSS, life insurance premiums, children’s tuition fees in India, and home loan principal on Indian property. The same 1.5 lakh cap applies.
Do I need to submit 80C proofs to the income tax department?
You submit proofs to your employer for lower TDS, not to the department. But keep all investment proofs for at least 6 years. The assessing officer can ask for them during scrutiny.
What happens to 80C if I sell the house within 5 years?
The 80C deductions claimed on home loan principal in earlier years get reversed. They are added back to your taxable income in the year of sale. The 5-year holding rule also applies to the stamp duty deduction.
Final Word
The 80C deduction list is long, but your strategy should be short: max out EPF automatically, add PPF or ELSS for the gap, use NPS for the extra ₹50,000, and never buy a product in March that you would not buy in April. Pair this with our our tax-saving guides on regime selection and HRA to build a complete tax plan — and file before the ITR filing last date, not after it.