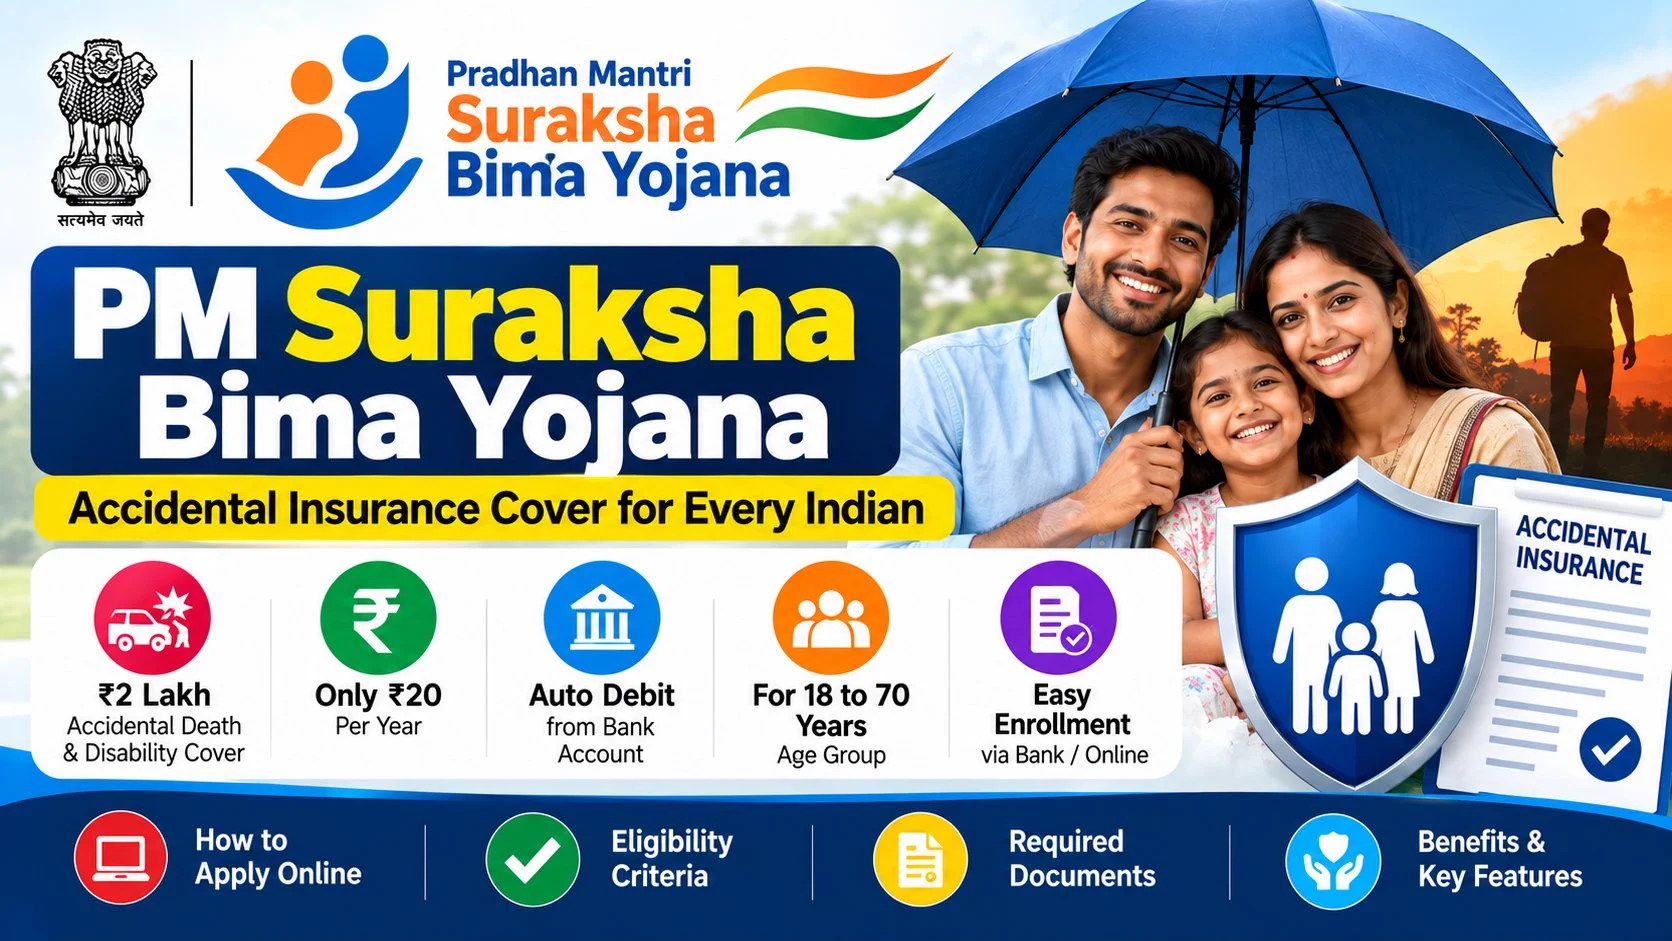

Road accidents in India kill over 1.5 lakh people every year — and for a daily-wage family, one accident can wipe out years of savings in a single hospital bill. What if I told you the government offers ₹2 lakh of accident insurance for less than the price of a cutting chai per month? That is exactly what the PM Suraksha Bima Yojana does, and most eligible people still haven’t enrolled.
✅ This guide is based on official government sources and notifications. Last verified: October 15, 2026. Scheme details, eligibility criteria, and benefit amounts are revised by the government from time to time — always cross-check the latest information on the official portal before applying.
If you want to understand pm suraksha bima yojana fully — what it covers, who can join, how the ₹20 premium works, and how your family actually claims the money — this guide walks you through every step. No jargon, no skipped steps.
What Is PM Suraksha Bima Yojana (PMSBY)?
Pradhan Mantri Suraksha Bima Yojana, launched in May 2015 by the Ministry of Finance, is a government-backed accident insurance scheme. It is designed for one simple purpose: to give ordinary Indians — especially daily-wage earners, farmers, small traders, and students — a financial safety net against accidents at a premium almost anyone can afford.
Here is the deal in one line: pay ₹20 once a year, and you (or your nominee) get up to ₹2 lakh if an accident causes death or total disability. There is no medical test, no agent commission drama, and no complicated paperwork to join. Your bank does most of the work through auto-debit.
The scheme runs on a yearly cycle from 1 June to 31 May. You enroll once, give consent for auto-debit, and the ₹20 premium is deducted from your savings account every year before 1 June. As long as the debit succeeds, your cover continues.
PMSBY at a Glance
| Detail | Information |
|---|---|
| Scheme name | Pradhan Mantri Suraksha Bima Yojana (PMSBY) |
| Launched | May 2015, Ministry of Finance |
| Type | Accident insurance (death + disability due to accident only) |
| Premium | ₹20 per year, auto-debited from savings account |
| Cover | ₹2 lakh (death / total disability), ₹1 lakh (partial disability) |
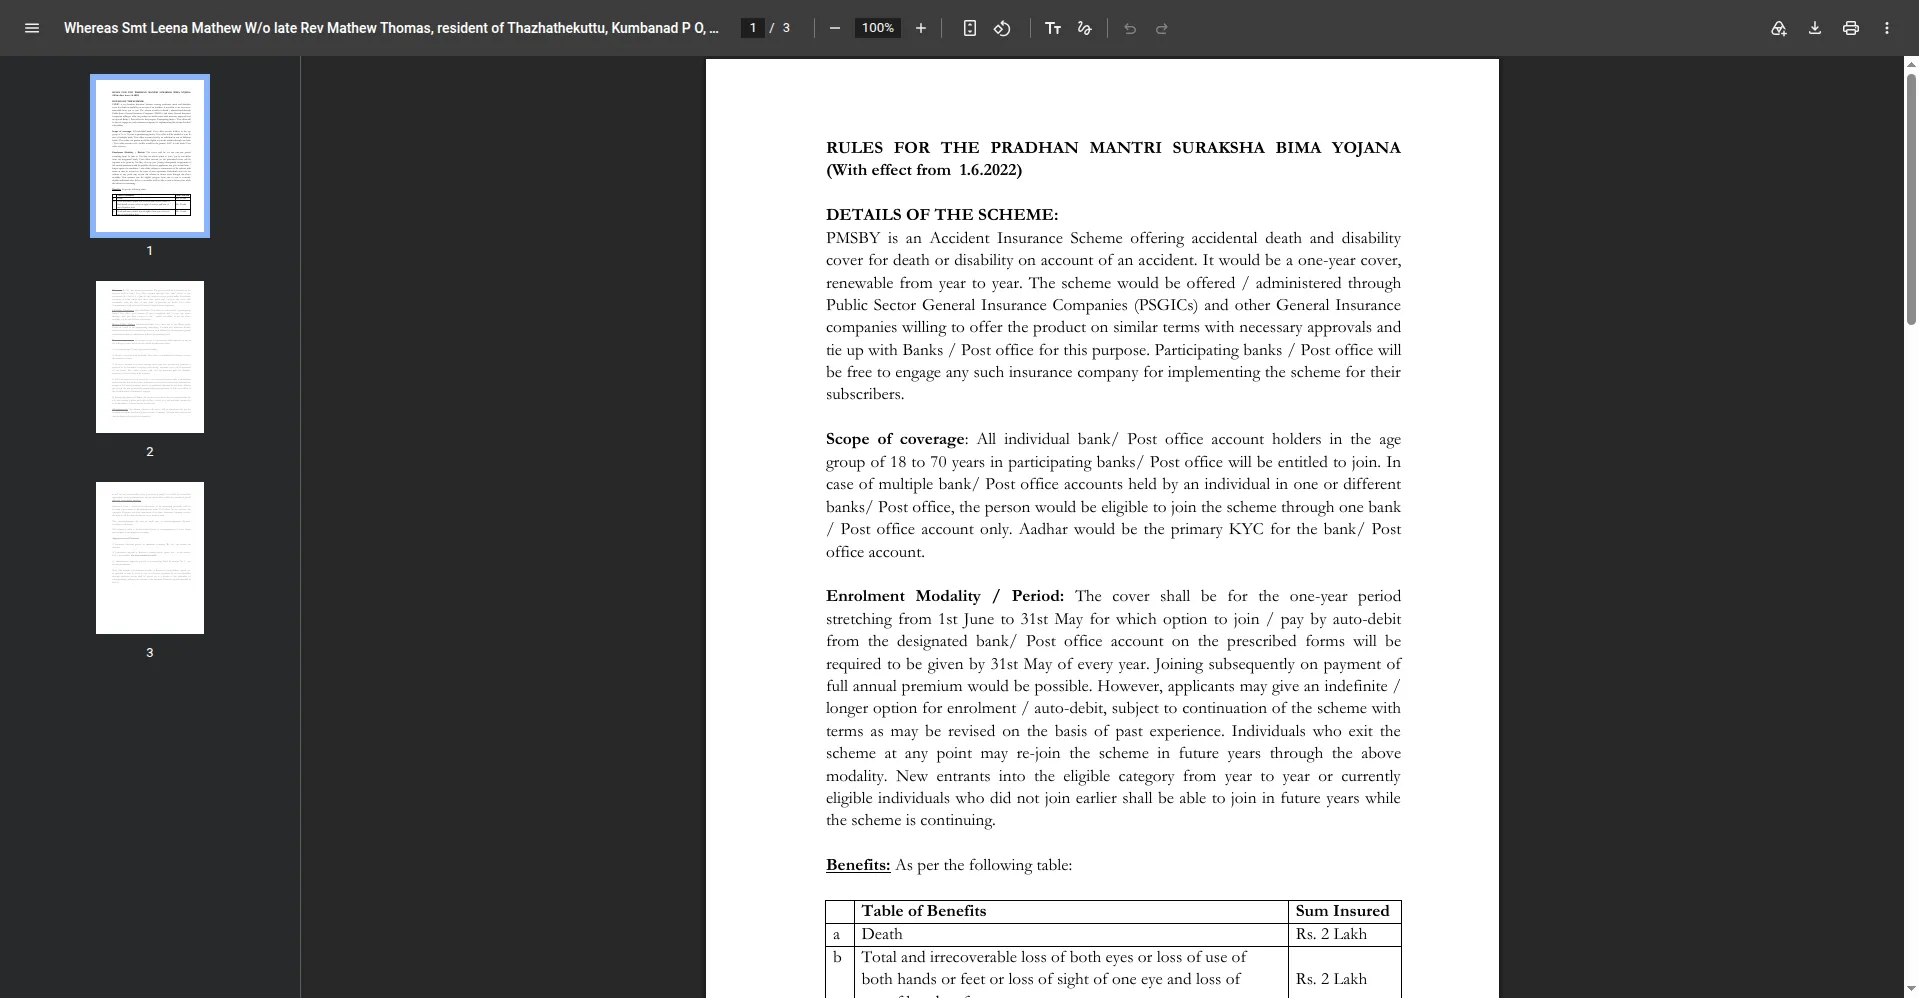
| Eligibility | Age 18–70, savings bank or post office account |
| Cover period | 1 June to 31 May (renewable yearly) |
| Official website | jansuraksha.gov.in |
The ₹20 Premium, Explained Simply
The suraksha bima yojana premium is the most talked-about part of this scheme, and for good reason. ₹20 per year breaks down like this:
- Per month: about ₹1.67
- Per day: about 5.5 paise — literally less than a toffee
- Payment mode: only through auto-debit from your savings account, in one instalment
- When it is deducted: on or before 1 June each year, for the cover period starting 1 June
A quick history note: when PMSBY launched, the premium was ₹12 per year. It was revised to ₹20 per year from 1 June 2022 to keep the scheme sustainable for insurers. Even after the hike, it remains one of the cheapest insurance products in the country.
Important: the premium must be in your account when the bank attempts the debit. If your balance is too low between late May and early June, the debit fails — and your cover for the entire year lapses. Keep at least ₹20 (plus a small buffer) in the linked account during the renewal window.
How Much Money Does PMSBY Pay? (Coverage Table)
A common search — “pmsby me kitna paisa milta hai” — has a precise official answer. The benefits, as notified by the government, are:
| Event | Sum Insured |
|---|---|
| Accidental death | ₹2,00,000 (paid to nominee) |
| Total and irrecoverable loss of both eyes, or loss of use of both hands or feet, or loss of sight of one eye plus loss of use of one hand or foot | ₹2,00,000 |
| Partial disability: total and irrecoverable loss of sight of one eye, or loss of use of one hand or foot | ₹1,00,000 |
Two things to note. First, this is a pure risk cover — there are no maturity benefits. If nothing happens during the year (which is what everyone hopes), the ₹20 simply bought you peace of mind. Second, hospital and treatment expenses after an accident are not covered; the scheme pays the lump sum for death or listed disabilities only.
Who Can Join? PMSBY Eligibility Criteria
The eligibility rules are deliberately simple so that enrolment stays easy:
- Age: 18 to 70 years (completed years). Cover ends when you turn 70.
- Account: an individual savings bank account or post office savings account with a participating bank/post office.
- Aadhaar: the account should preferably be Aadhaar-linked; if not, attach a copy of your Aadhaar with the form.
- Consent: you must sign the consent-cum-declaration form authorising yearly auto-debit of ₹20.
- One account only: if you hold multiple savings accounts, you may join PMSBY through only one of them. If premium gets debited from more than one account by mistake, the cover stays capped at ₹2 lakh and the extra premium is forfeited — so pick one account and stick to it.
There is no medical examination and no health declaration. If you meet the age and account conditions, you are in.
How to Enroll in PMSBY: Step-by-Step
You can join both offline and online. Pick whichever is easier for you.
Method 1: Offline (Bank Branch / Post Office)
- Visit the bank branch or post office where you hold your savings account.
- Ask for the PMSBY enrolment form (also downloadable from jansuraksha.gov.in).
- Fill in your name, address, date of birth, nominee name and relationship, and account number.
- Sign the consent for auto-debit of the ₹20 annual premium.
- Submit the form. The bank will activate your cover and debit the premium.
- Keep the acknowledgement slip safely — it is your proof of enrolment.
Method 2: Online (Net Banking / Mobile Banking)
- Log in to your bank’s net banking portal or mobile banking app.
- Go to the Insurance or Social Security Schemes section.
- Select PMSBY / Suraksha Bima Yojana.
- Confirm your details, add or verify your nominee, and give auto-debit consent.
- Submit. You will get an acknowledgement — save or screenshot it.
Many banks also allow enrolment through the JanSuraksha portal itself. If your bank’s app doesn’t show the option clearly, the branch visit (Method 1) takes about 15 minutes and always works.
Auto-Debit, Renewal, and When Cover Lapses
Understanding the renewal cycle prevents the most common reason people lose their cover without realising it.
- Cover period: 1 June to 31 May every year.
- Renewal debit: the ₹20 premium is auto-debited on or before 1 June for the coming year.
- Joining mid-year: if you enroll after 1 June, your cover starts from the date the premium is debited and runs till 31 May. You still pay the full ₹20.
- Long-term option: you can opt for multi-year auto-debit consent so you never have to think about renewal.
Your cover lapses if: you turn 70, you close the linked bank account, your account doesn’t have enough balance when the premium debit is attempted, or you submit a cancellation request. The good news: you can rejoin later by submitting a fresh consent form and paying the annual premium — there is no penalty for rejoining.
PMSBY Claim Process: How Your Family Gets the Money
This is the section most articles gloss over — but it’s the entire point of insurance. Here is the pmsby claim kaise kare process, step by step:
Step 1: Inform the Bank Immediately
The insured person, or the nominee (in case of death), should contact the bank branch where the PMSBY-linked account is held, as soon as possible after the accident.
Step 2: Get and Fill the Claim Form
Collect the PMSBY claim-cum-discharge form from the bank branch, the insurance company’s office, or download it from the official portal. Fill it completely and accurately.
Step 3: Submit Within 30 Days
Submit the filled form to the bank branch within 30 days of the accident, along with the supporting documents listed below.
Step 4: Bank Verification (Up to 30 Days)
The bank verifies your account details, the auto-debit record, the nomination, and certifies the claim form. It then forwards the case to the insurance company within 30 days of receiving it.
Step 5: Insurer Processing (Up to 30 Days)
The insurance company confirms you are on the master policy list and processes the claim within 30 days of receiving the documents from the bank.
Step 6: Money Credited
The approved amount is credited directly to the nominee’s bank account (death claim) or the insured’s account (disability claim). If no nominee was named, the legal heir must produce a succession certificate.
Documents Required for PMSBY Claim
| Claim Type | Documents Needed |
|---|---|
| Death claim (filed by nominee) | Claim form, death certificate, original FIR / Panchnama, post-mortem report (where applicable), nominee’s Aadhaar and bank details, discharge certificate |
| Disability claim (filed by insured) | Claim form, original FIR / Panchnama, disability certificate issued by a Civil Surgeon, hospital discharge records, Aadhaar and bank details, discharge certificate |
Is an FIR always required? For vehicle accidents, drowning, or crimes like murder, yes — an FIR is needed. For accidents like a fall from a tree or an animal attack, immediate hospital records serve as evidence. Some documentary proof of the accident is essential in every case.
What PMSBY Does NOT Cover (Exclusions)
Knowing the exclusions avoids nasty surprises at claim time:
- Suicide and self-inflicted injuries are not covered. (Death by murder is covered, with an FIR.)
- Natural death or death from illness is not covered — PMSBY is accident-only.
- Non-permanent / temporary disabilities are excluded; only the listed irrecoverable losses qualify.
- Hospital and treatment expenses are not reimbursed.
- Accidents from natural calamities (floods, earthquakes) are covered, as long as they meet the death/disability definitions.
PMSBY vs PMJJBY: Which One Do You Need?
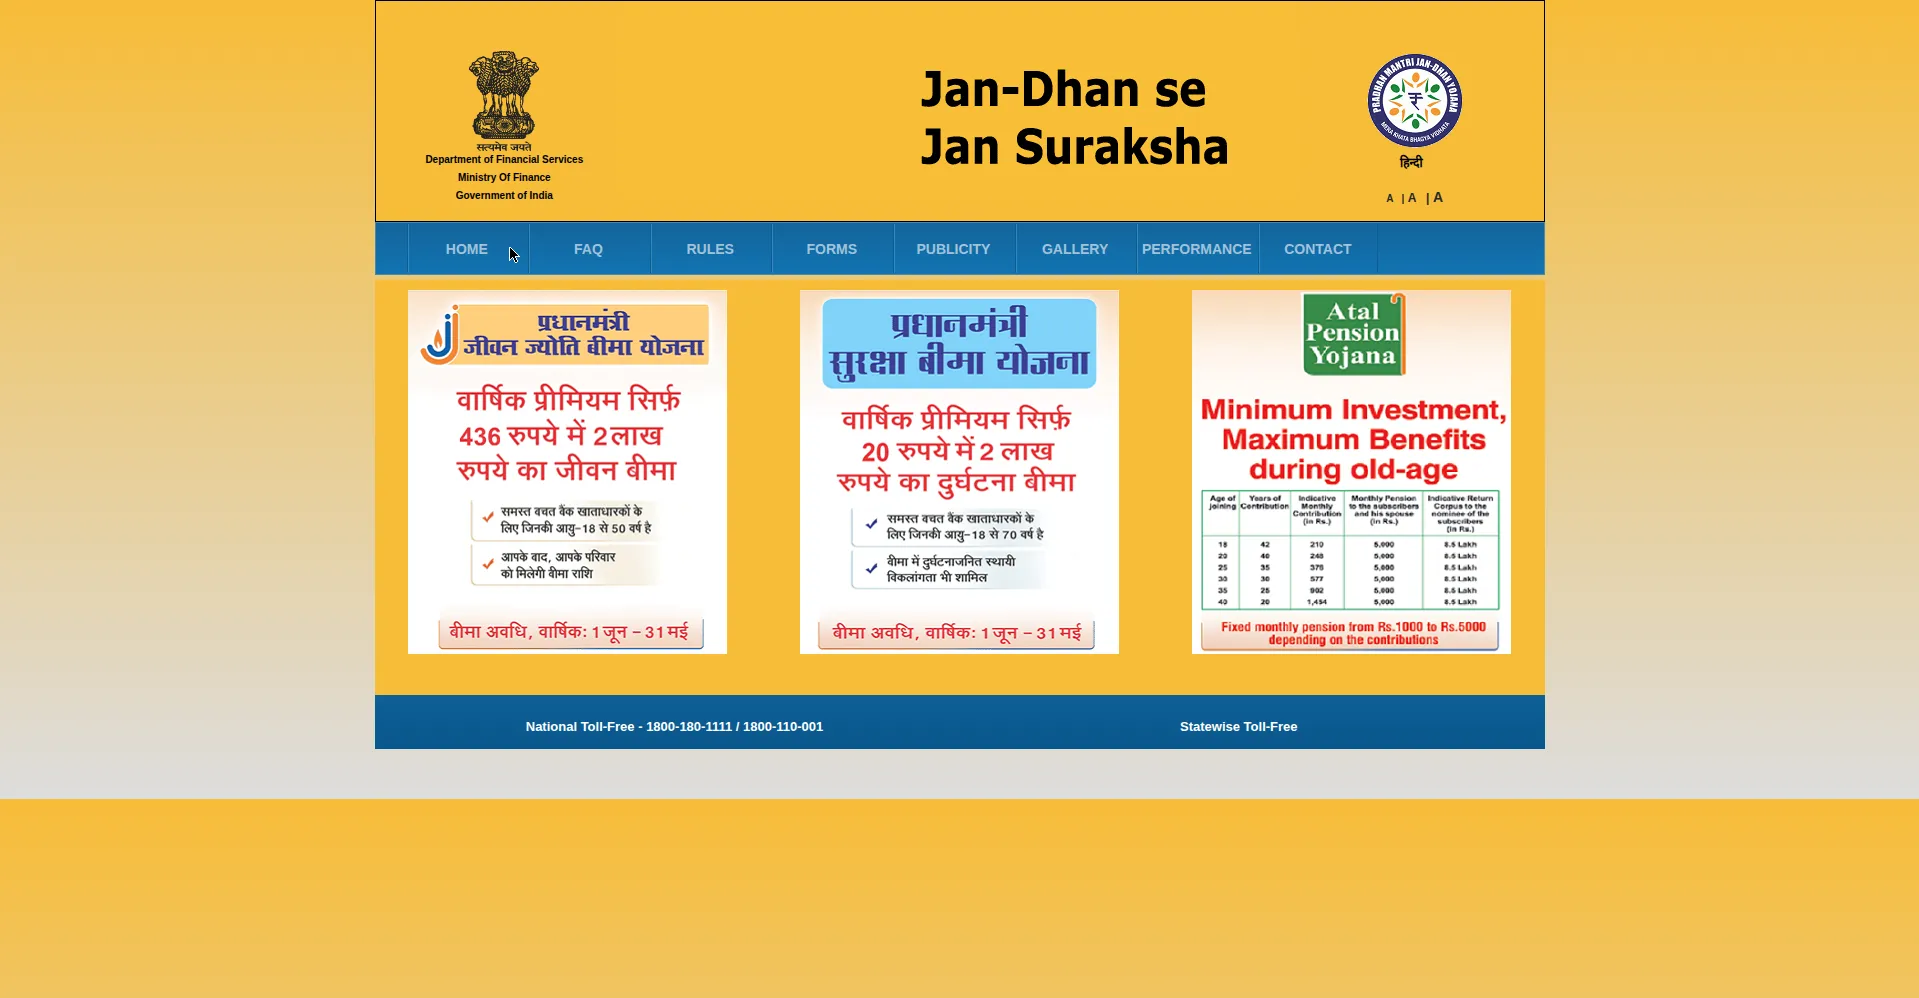
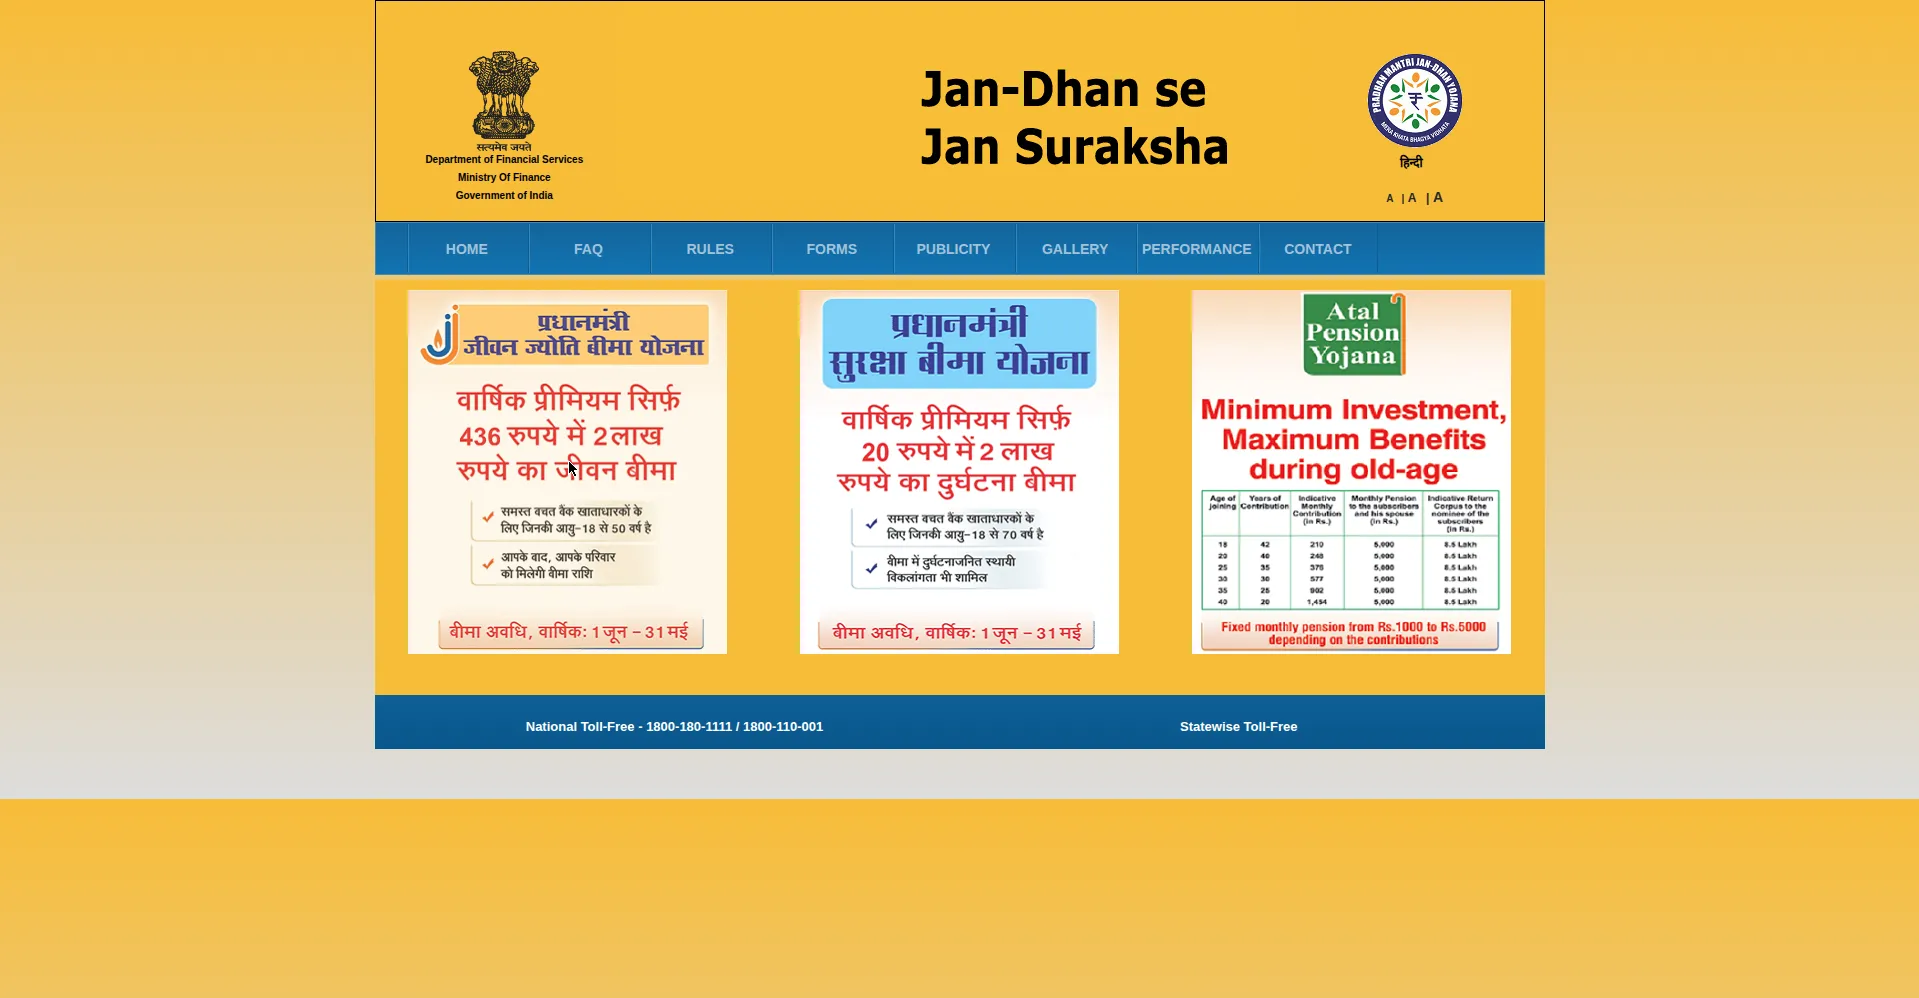
This is the most common confusion, so let’s settle it. PMSBY’s companion scheme is the Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) — a life insurance scheme, not an accident scheme. They cover different risks, which is why the government promotes them together.
| Parameter | PMSBY | PMJJBY |
|---|---|---|
| Type | Accident insurance | Life (term) insurance |
| Premium | ₹20/year | ₹436/year |
| Age eligibility | 18–70 years | 18–50 years (cover till 55) |
| What it pays | ₹2L accidental death / total disability; ₹1L partial disability | ₹2L on death due to any reason |
| Disability cover | Yes | No (pays only on death) |
| Illness/natural death | Not covered | Covered |
Can you take both? Yes — and you should consider it. Together they cost ₹456 per year (₹20 + ₹436) and give your family up to ₹4 lakh of combined protection: PMJJBY pays if death occurs from any cause, while PMSBY also covers accident-related disability — the scenario where PMJJBY pays nothing because the person survived. For anyone with dependents, skipping both is a risk not worth taking.
If you’re building a full safety net, also look at the Atal Pension Yojana for retirement income — insurance protects your family today, pension protects you tomorrow. And if you run a small business, the PM Mudra Loan Yojana guide explains collateral-free loans up to ₹20 lakh.
5 Mistakes That Can Void Your PMSBY Claim
- Enrolling through two accounts. Cover stays capped at ₹2 lakh and the extra premium is forfeited. Use one account only.
- Zero balance in May. If the ₹20 debit fails, you are uninsured for the whole year. Keep a buffer in the linked account.
- Outdated nominee details. Wrong nominee information delays settlement for months. Update it at your branch if your family situation changes.
- Missing the 30-day claim window. File the claim form at the bank within 30 days of the accident — delays complicate everything.
- Assuming illness is covered. PMSBY pays only for accidents. A heart attack or cancer death gets nothing under this scheme (that’s what PMJJBY is for).
Who Benefits Most From PMSBY?
While anyone aged 18–70 with a savings account can join, the scheme matters most for specific groups:
- Daily-wage earners and construction workers: the highest accident exposure and the least savings to fall back on. ₹20 a year is genuinely affordable even on irregular income.
- Farmers and agricultural labourers: farm machinery, pesticides, and field work carry real accident risk. PMSBY pairs well with crop insurance thinking — protect the crop and the farmer.
- Gig and delivery workers: two-wheeler riders face India’s deadliest accident statistics daily. If you ride for a living, this is non-negotiable.
- Small traders and street vendors: no employer, no ESI, no group cover — PMSBY is often their only insurance.
- Students above 18: college students commuting daily get meaningful cover for pocket change.
If you fall in any of these groups and haven’t enrolled, the branch visit takes 15 minutes. There is no cheaper way to buy this much protection.
Tax Benefits of PMSBY
Two tax provisions apply:
- Section 80C: the ₹20 premium you pay qualifies for deduction under Section 80C of the Income Tax Act, 1961 (within the overall ₹1.5 lakh 80C limit).
- Section 10(10D): the claim amount your nominee receives — the ₹2 lakh or ₹1 lakh payout — is exempt from income tax.
At a ₹20 premium the 80C saving is tiny in absolute terms, but the 10(10D) exemption on the payout is genuinely valuable: your family receives the full claim amount with no tax cut.
🔗 Related Government Schemes
Frequently Asked Questions
1. PMSBY kya hai?
Pradhan Mantri Suraksha Bima Yojana ek sarkari accident insurance scheme hai. Sirf ₹20 saal me aapko accident me death ya disability par ₹2 lakh tak ka cover milta hai. Age 18–70, savings account holders eligible hain.
Premium har saal 1 June se pehle auto-debit hota hai aapke linked savings account se. Cover period 1 June se 31 May tak hota hai. May ke end me account me kam se kam ₹20 balance rakhein.
3. PMSBY me suicide cover hota hai kya?
Nahi. Suicide aur self-inflicted injuries PMSBY me covered nahi hain. Lekin murder (FIR ke saath) aur natural calamity se hui death/disability covered hai.
4. Kya main PMSBY aur PMJJBY dono le sakta hoon?
Haan, bilkul. Dono alag risks cover karte hain — PMSBY accident, PMJJBY kisi bhi wajah se death. Dono ka total premium sirf ₹456/year hai.
5. PMSBY claim kaise kare?
Accident ke 30 din ke andar bank branch me claim form jama karein, FIR, death/disability certificate aur discharge certificate ke saath. Bank 30 din me verify karke insurance company ko bhejta hai, jo 30 din me payment karta hai.
6. Agar account me balance kam hua to kya hoga?
Agar renewal ke time premium debit nahi ho paya to us saal ka cover lapse ho jayega. Aap baad me fresh form bharke dobara join kar sakte hain — koi penalty nahi hai.
Final Word
At ₹20 a year — roughly 5 paise a day — PMSBY is the cheapest meaningful insurance an Indian family can buy. It won’t replace a full term plan, but for crores of households with no safety net at all, it is the difference between dignity and destitution after an accident. Enroll through your bank, keep ₹20+ in the account every May, tell your nominee where the papers are, and consider pairing it with PMJJBY for ₹456/year total protection.
For official forms and the latest notifications, visit jansuraksha.gov.in.